Nomura and Aventus (TSXV: AVTS), an integrated insurance and alternative asset management company backed by CC Capital, have launched a joint venture designed to offer investors access to differentiated opportunities, primarily in securitized products and private credit.
Through Misura, clients gain access to end-to-end asset sourcing and origination, alongside specialized investment advisory and portfolio management. This collaboration uniquely leverages the capabilities of Nomura’s renowned securitized products and private credit franchise to create bespoke capital solutions, combining them with Aventus’s expertise in underwriting and managing credit investments, as well as the extensive track record of its sponsor, CC Capital.
“This partnership brings together the agility and capabilities of a specialized investment manager with the origination reach of a global investment bank to create a highly differentiated credit platform. In a market where origination, structuring expertise, and investment discipline are decisive, we believe our complementary strengths provide a solid foundation for an enduring business that builds upon the CC Capital and Aventus platform and positions it to capture attractive opportunities across both the full credit spectrum and special situations,” stated Chinh Chu, Founder and Senior Managing Director of CC Capital and Executive Chairman of Aventus.
For his part, Chris Willcox, Deputy President, Head of Wholesale, and Chair of the Investment Management Division at Nomura, noted: “Expanding our securitized products and private markets solutions business is a top strategic priority, and through this joint venture, we have succeeded in broadening our footprint by leveraging the scale of Nomura’s franchise alongside Aventus’s investment management capabilities. We are pleased to collaborate with the CC Capital and Aventus teams on the launch of Misura.”
Regarding the alliance, Gordon Sweely, Head of Securitized Products and Private Credit at Nomura, commented: “Misura brings together Nomura’s industry-leading expertise, global reach, and specialized focus to deliver tailored financing solutions to clients. This partnership expands our distribution capabilities across the entire capital structure, enabling us to bring Nomura’s premier platform to a broader client base.”
And Andrew Rabinowitz, Chief Executive Officer of Misura Asset Management, concluded: “We have built a platform that combines specialized investment talent, proven across multiple market cycles, with a large-scale origination engine, while preserving independence in underwriting and investment decision-making. I am excited about what Nomura and Aventus can create together, and I thank the entire Nomura team for their pivotal role in developing the platform.”
From Nvidia to McDonald’s, Intel, and Nestlé, romantic scandals, conflicts of interest, and the personal conduct of top executives have demonstrated that a company’s reputation can also rest in the hands of whoever occupies the corner office.
The fall of Jensen Huang not only represents an unexpected episode in Nvidia’s history, but also places back on the table one of the most delicate issues in corporate governance: how far does a CEO’s private life extend when personal decisions can compromise the interests of a company, its shareholders, and thousands of employees?
Private life, yet public
The answer is not simple, yet there is something that large corporations are increasingly clear about: the conduct of the person holding the top executive position is not an exclusively personal matter when it can generate conflicts of interest, call into question the enforcement of internal rules, or compromise the organization’s reputation.
The case of Huang, who stepped down this Thursday, November 12, from the presidency, chief executive role, and his seat on Nvidia’s board of directors after 33 years at the helm of the company, constitutes a particularly illustrative example.
The departure occurred after the businessman publicly acknowledged having been unfaithful to his wife and reports surfaced regarding romantic relationships allegedly involving a woman suspected of maintaining ties to Chinese intelligence services and a Nvidia executive who, according to media reports, reported directly to him. The company had previously opened an independent investigation and retained external legal counsel. Although the resignation statement did not expressly attribute the decision to a specific cause, the sequence of events turned the personal episode into a corporate governance and reputational crisis.
Investor reaction was immediate. Nvidia shares plunged around 14% during early trading on Thursday, November 12, touching an intraday low of $148.80 before ultimately closing at $166.19, down 4.34%.
The company, whose market capitalization hovers around $4.2T, had to announce that Colette Kress, until then Chief Financial Officer, would assume the interim chief executive role while the board searches for a permanent successor. The market reacted not only to the departure of one of the most influential figures of the artificial intelligence revolution, but also to the uncertainty entailed by losing the man who built much of the company’s technological and strategic identity.
Other corporate scandals
The case of Nvidia’s CEO is not inaugurating a new category of corporate scandal. In fact, one of the closest precedents occurred at Intel in 2018, when Brian Krzanich had to resign as CEO after an internal investigation confirmed he had engaged in a consensual relationship with an employee, in violation of the company’s non-fraternization policy applicable to all executives.
The board’s decision was decisive: if the rest of the workforce was obligated to respect internal rules, the company’s top executive could not place himself above them. The similarity to the Nvidia episode is evident: the corporate problem does not necessarily consist of passing judgment on a romantic relationship, but rather determining whether a reporting relationship, a conflict of interest, or a breach of the rules meant to guarantee impartiality in business decisions exists.
A year later, in 2019, McDonald’s faced a similar situation. Its then-CEO, Steve Easterbrook, was fired after the company discovered he was engaged in a consensual romantic relationship with an employee, something prohibited by its internal policies.
However, the matter did not end with his departure. A subsequent investigation revealed other undisclosed relationships with employees and raised questions regarding the information he had provided to the company. The case escalated to the U.S. Securities and Exchange Commission (SEC), which in 2023 sanctioned the former executive for making false or misleading statements to investors regarding the circumstances of his termination.
It also scrutinized McDonald’s disclosure of his separation agreement, which had allowed him to retain compensation exceeding $40M. The company ultimately recovered approximately $105M in cash and stock. The lesson extended far beyond infidelity: concealing information, manipulating internal processes, or prioritizing personal interests can turn into an issue directly tied to shareholder protection.
More recently, in September 2025, Nestlé fired its CEO Laurent Freixe after confirming he was maintaining an undisclosed romantic relationship with a direct subordinate, in violation of its code of business conduct.
The investigation took place following internal complaints related to potential preferential treatment toward the employee. The episode underscored that integrity policies are not merely compliance mechanisms for operational tiers: they can also determine the tenure of a multinational’s top executive. And, above all, that the issue takes on another dimension when a personal relationship can influence promotions, compensation, evaluations, or decisions regarding company resources.
Loss of trust and other scandals, the blow to corporate culture
Nevertheless, romantic relationships represent only part of a much broader list of behaviors that have ended up shaking major corporations and eroding market confidence.
Volkswagen was at the center of one of the largest industrial scandals of recent decades with the so-called Dieselgate, uncovered in 2015, when it was revealed that the automaker had used software to manipulate emissions tests on its diesel vehicles. The crisis triggered the resignation of its then-CEO, Martin Winterkorn, in addition to fines, settlements, and a deterioration of its global reputation. In this instance it was not a matter of romantic conduct, but rather business decisions that compromised an organization’s ethics, transparency, and accountability toward its customers and regulators.
Enron represents another of the most forceful examples of how ambition and an absence of controls can destroy corporate trust. The U.S. energy giant collapsed in 2001 after complex accounting practices, debt concealment, and manipulation of its financial results came to light.
Its top executives, among them Kenneth Lay and Jeffrey Skilling, became associated with one of the largest corporate frauds in U.S. history. The bankruptcy wiped out thousands of jobs and retirement savings belonging to workers and investors. The case made clear that a company can project an image of success, innovation, and growth for years while its top leaders erode from within the very principles meant to sustain it.
There is also the case of Wells Fargo, where the opening of millions of bank accounts without customer authorization, driven by aggressive sales targets and high-pressure practices placed on employees, led to a crisis of confidence that culminated in the departure of its CEO, John Stumpf, in 2016.
Uber, for its part, saw its corporate culture falter under the leadership of Travis Kalanick, amid allegations of harassment, management failures, and scrutiny over the workplace environment, until he stepped down as chief executive in 2017. These are distinct episodes, yet they share a common thread: when an organization’s culture ceases to align with the principles it proclaims, the cost ultimately transfers to its reputation, its ability to attract talent, and the confidence of its investors.
What unites these cases is not necessarily the nature of the infractions, but the position of those at the center of them. A CEO is not just another employee. A CEO manages other people’s capital, represents the organization before the markets, participates in strategic decisions, and bears a special responsibility in building a culture of integrity.
For that reason, romantic relationships with subordinates, undisclosed conflicts of interest, abuse of power, manipulation of information, accounting fraud, or the concealment of problems cannot be analyzed solely from a personal standpoint. At a publicly traded company, any of those behaviors can carry financial, legal, and reputational consequences.
The issue is also tied to a paradox of corporate leadership: companies routinely demand strict levels of compliance, transparency, and accountability from their employees, yet when irregularities involve their top executives, boards of directors face a far more complex test. They must decide whether to protect a figure who may be vital to the business or uphold the rules, even when doing so means losing a founder, a successful executive, or the person who publicly represents the company. Nvidia has just confronted that dilemma, and its decision will carry consequences reaching far beyond Huang’s succession.
Ultimately, Wall Street can forgive strategic missteps, quarterly earnings below expectations, or even misguided investment decisions if there is a reasonable explanation and a path to recovery. What proves far harder to restore is trust when investors begin questioning the integrity of those leading a company.
The private life of a CEO should be, in principle, precisely that: private. Yet when personal decisions compromise impartiality, safety, transparency, or compliance with corporate rules, it ceases to be so. Nvidia, Intel, McDonald’s, and Nestlé, to name a few cases, serve as reminders that at major corporations power also entails obligations. No CEO, however successful or indispensable they may appear, should stand above them. The market knows it, and the market remembers.
What do a goalkeeper who played in 6 World Cups and a golfer who reached the 6th spot in the world rankings have in common? At first glance, their stories seem to belong exclusively to professional sports. However, their experiences offer lessons that also have a place in financial markets, business, and investment strategies: talent can open doors, but it is discipline, perseverance, and the ability to make decisions that allow one to stay at the top.
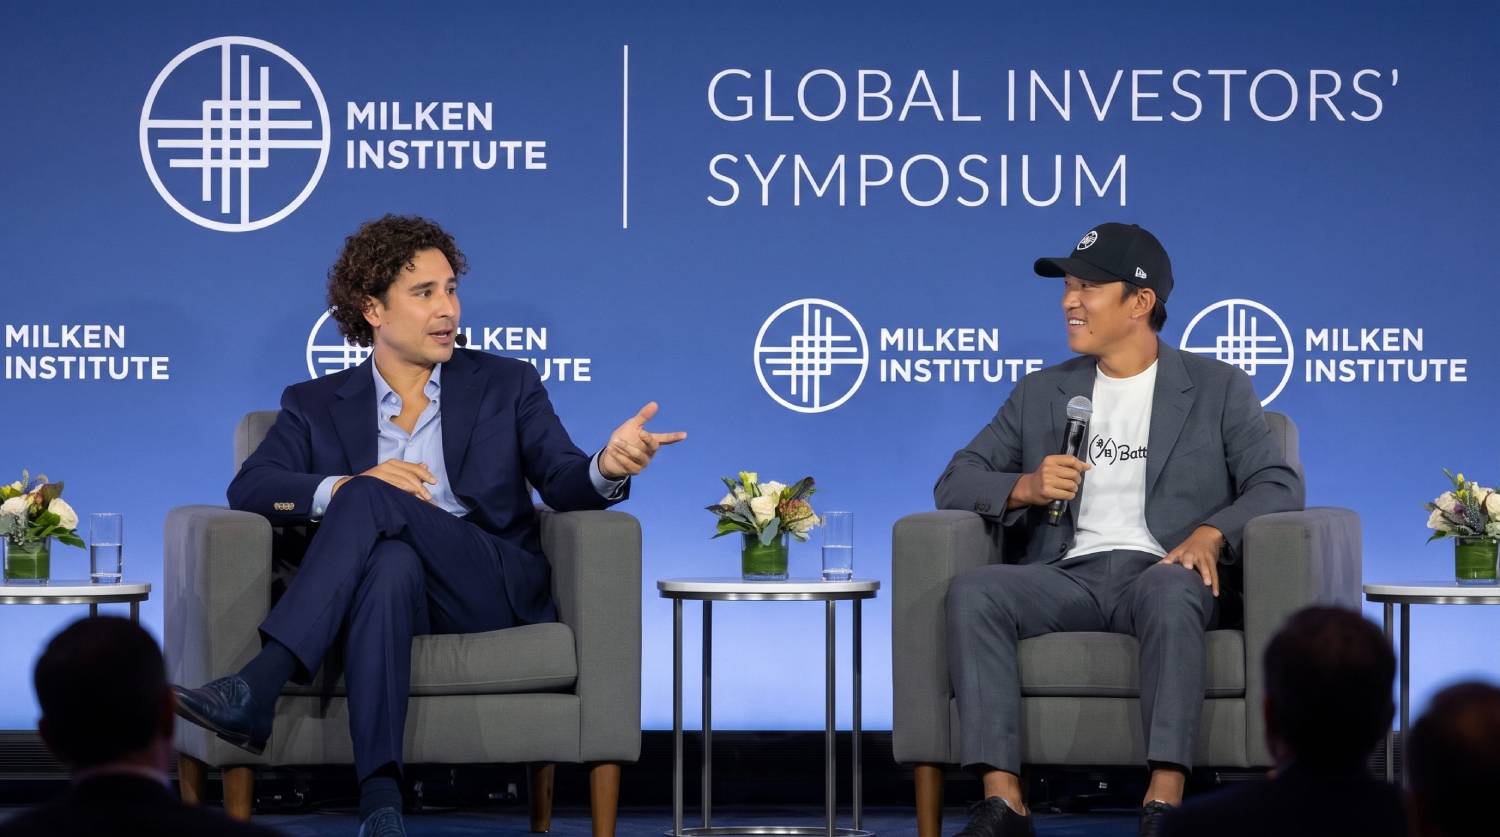
That was the essence of 2 conversations that Guillermo Ochoa and Anthony Kim held on October 28 during a gathering organized by the Milken Institute in Mexico City. Although their careers unfolded in different disciplines and their personal circumstances were vastly different, both agreed on a fundamental idea: success is not a final destination, but a process that demands preparation, learning, and the capacity to get back up after every setback.
The reflections of the former Mexican goalkeeper, whose career spanned more than 2 decades and took him to 6 World Cups, and of the American golfer, who reached the international elite before turning 25 and later faced a prolonged personal and professional crisis, make it possible to draw a parallel with the world of investing. In both arenas, outcomes depend as much on preparation as on how risk is managed, uncertainty is confronted, and mistakes are answered.
Memo Ochoa: building wealth also demands discipline and long-term vision
For Guillermo Ochoa, the end of his cycle as a professional footballer did not mean abandoning competition, but rather transferring what he learned over more than 22 years into a new stage: business, investments, and building a legacy. In conversation with Juan Manuel Valle, CEO of Afore Coppel, the former goalkeeper explained that one of his priorities after taking a period of rest was to become more directly involved in managing the wealth he had built during his career. A decision that, as he recounted, did not arise spontaneously, since during his years as a footballer he had sought to diversify his income streams and prepare for the moment he left the pitch.
Ochoa brought up a reality that often goes unnoticed in professional sports: athletes begin generating substantial income at very young ages, yet their earning capacity also ends much earlier than that of other professionals. As an example, he noted that a footballer typically experiences their peak earning years between ages 20 and 40, whereas other professionals may reach their highest economic capacity between ages 40 and 60 or 65. That difference forces athletes to think ahead about their financial future and understand that a high salary does not necessarily equate to solid wealth.
His strategy consisted of advancing gradually. He began with mutual funds, bonds, and fixed-income products, both short- and long-term; later he moved toward emerging companies and startups, in some cases through partnerships in which he participates as a partner rather than merely as a commercial brand ambassador. He also incorporated real estate investments and protection mechanisms such as life and major medical insurance.
The former national team player acknowledged that not all of his investments worked out. He recalled unsuccessful experiences in businesses such as gas stations, pyramid schemes, and startups, including a video game from which he expected substantial growth. Nevertheless, he emphasized that those missteps allowed him to identify risks, learn to evaluate opportunities better, and distrust proposals that promise extraordinary returns.
His philosophy, he explained, remains conservative. First he sought to build a solid wealth foundation and, once a degree of stability was achieved, began considering higher-risk investments. Experience also taught him to recognize when an opportunity does not match his profile and when it is better to stay on the sidelines of volatility. In that sense, he summed up one of his main financial lessons in a simple recommendation: save consistently and avoid unnecessary expenses.
Yet perhaps Ochoa’s most relevant reflection went beyond his own experience. He considered that Mexican sports has unfinished business in financial education, as many athletes do not know how to manage their income, where to invest, how to protect their wealth, or whom to turn to for specialized advice. He warned that some athletes end up losing their resources just a few years after earning them, whether due to lack of knowledge, investing in businesses they do not understand, or trusting the wrong people.
Consequently, he proposed fostering a culture of saving and wealth management starting at the youth development stages, incorporating tools to plan for retirement, purchase insurance, invest in real estate, and receive tax and financial advisory services. His purpose in this new chapter, he explained, is to help close those gaps through projects combining sports, education, technology, and business.
His closing reflection captured the shift in priorities: after dedicating a large part of his life to guarding a goal, he now wants to protect his family’s wealth and build a legacy that enables others to go further.
Anthony Kim: after hitting rock bottom, the importance of starting over
Anthony Kim’s story offers another perspective on perseverance and the ability to rebuild oneself. The American golfer, who rose to 6th in the world rankings before turning 25, enjoyed a meteoric career, yet also went through a particularly difficult personal period that kept him away from professional golf for more than 12 years.
In his conversation with Rodrigo Bettini, Managing Director at the Milken Institute, Kim recalled that his introduction to golf began when he was barely 2.5 years old, in an immigrant family whose parents held high expectations for his future. Behind his athletic upbringing was, above all, his mother’s sacrifice, having worked for years without vacations or days off to offer him opportunities she herself had never had.
That effort was one of his primary motivations. Kim acknowledged that much of his career was driven by the desire to repay his family’s sacrifices and enable his mother to stop working.
However, success arrived much faster than he was prepared to handle. Before receiving his first PGA Tour paycheck, he recalled, he was living on a futon in his coach’s basement and had barely $50 in his bank account. Then came the endorsements, the money, the recognition, and an environment in which, as he recounted, too many people told him everything he did was right. A lack of boundaries, bad company, and struggles with addiction and mental health ultimately led him into a dark period that kept him away from the sport for more than a decade.
Today, at 41 years old, sober and with a renewed outlook on life, Kim considers one of his greatest lessons to be understanding the importance of personal relationships and listening to those who genuinely want to help him. He admitted that in the past he pushed away people who pointed out his mistakes, while keeping close others who took advantage of his moments of vulnerability.
Rehabilitation also enabled him to develop a philosophy he now applies both to his personal life and to his return to professional golf: getting 1% better every day. Rather than focusing exclusively on major outcomes or goals difficult to control, Kim learned to set small, achievable objectives. It might mean spending several hours perfecting a shot, practicing putts, or completing a training session. What matters, he explained, is fulfilling the established purpose, regardless of whether immediate results are favorable.
That mindset also reshaped his relationship with defeat. He recalled that in his first tournament after returning to the LIV Golf circuit, he finished in last place, 33 strokes behind the leaders over 3 rounds. Although he admitted he remains a sore loser, he now understands that the outcome of a competition does not define a person’s worth nor should it become an obstacle to pressing forward.
His comeback, moreover, is driven by different motivations than his first stint as a professional. Sobriety, his wife, and especially his daughter gave him a different perspective on life’s priorities. Golf remains important, but being present for his family now comes first.
Kim also offered a recommendation for young athletes striving to reach the highest level: before focusing exclusively on winning, they need to build a foundation of personal stability they can fall back on when things go wrong. It is a lesson that can also be carried over into any professional field. Having a solid structure, surrounding oneself with trustworthy people, and developing habits that help navigate difficult moments can be just as important as talent or the opportunities that arise along the way.
Two disciplines, one shared lesson for investors
The experiences of Ochoa and Kim show that success takes different expressions, yet shares certain fundamentals. In sports, as in investing, talent and initial resources do not guarantee sustainable results. Discipline is needed to prepare, patience to wait for outcomes, intelligence to manage risks, and humility to acknowledge mistakes. Ochoa represents the importance of anticipating the future. He understood that his athletic career had an expiration date and that he needed to build wealth capable of sustaining his lifestyle beyond the pitch. His experience also demonstrates that diversifying, seeking advice, and not being seduced by extraordinary returns are fundamental decisions for protecting capital.
Kim, for his part, represents the capacity to rebuild. His trajectory serves as a reminder that even those who reach extraordinary heights can lose their way, and that coming back requires recognizing mistakes, changing habits, and establishing new priorities. His philosophy of improving 1% daily is, in essence, a wager on sustained growth rather than the pursuit of immediate results.
For an investor or a financial strategist, both stories carry a particularly valuable takeaway. The first is that generating resources is not enough: one must manage, protect, and grow them with a long-term vision. The second is that mistakes are part of the process, but the difference lies in learning from them and preventing them from becoming behavioral patterns.
There is also a lesson regarding one’s environment. Neither of them built his trajectory entirely alone. Ochoa recognized the importance of having advisors and people to guide him in his wealth decisions; Kim learned, after a difficult period, that surrounding oneself with people capable of telling the truth is indispensable to staying on course. In financial markets, where uncertainty, volatility, and high-pressure decisions are part of daily activity, those qualities take on special value. Knowing when to advance, when to wait, when to take on risk, and, above all, when to recognize that a decision was mistaken can make the difference between a successful strategy and a loss difficult to recover from.
In the end, the stories shared at the Milken Institute gathering left a reflection that transcends pitches and golf courses: true success does not consist solely of reaching the top, but of developing the ability to stay there, adapt when circumstances change, and find new reasons to keep moving forward. And perhaps that is the greatest overlap between a high-performance athlete and a good investor: both know that major victories are rarely built in a single day.
The pension industry is facing a paradigm shift: longevity, labor market transformation, and the technological revolution are forcing a rethink not only of how much workers must save, but also of how their assets are invested and, above all, how they are converted into income capable of sustaining them through longer retirement periods.
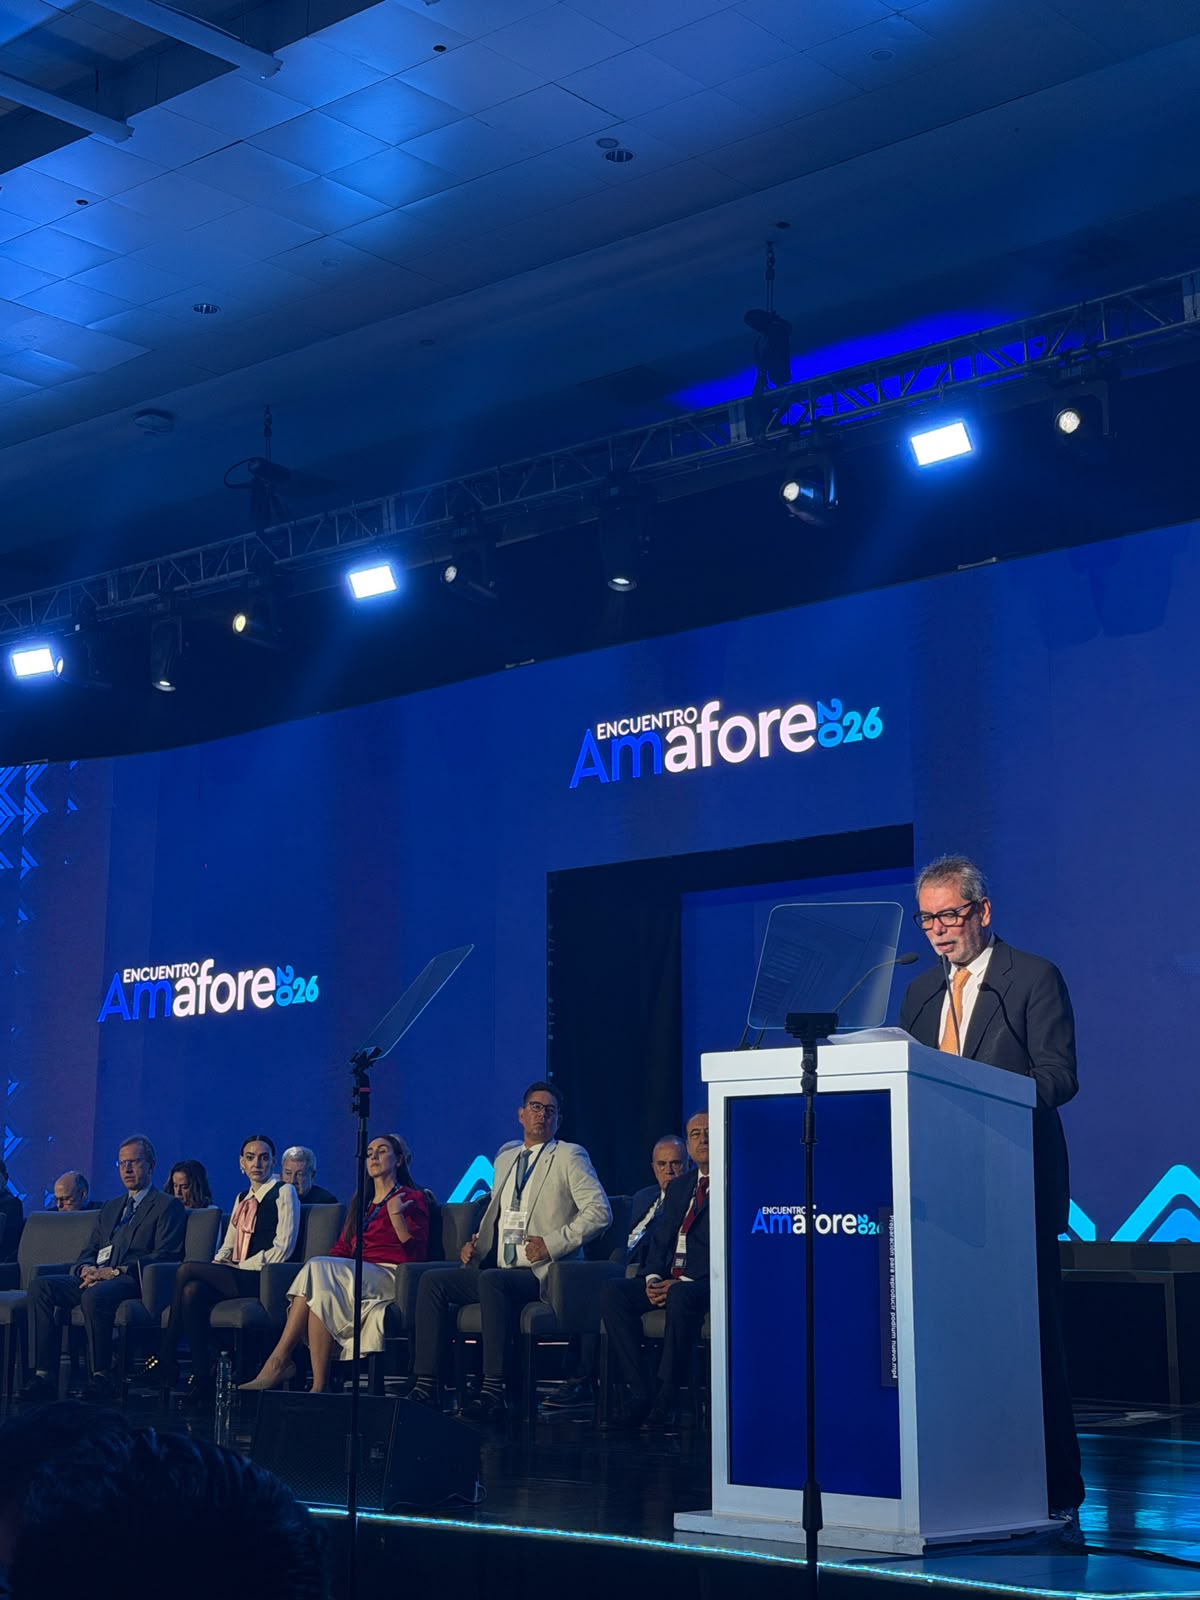
That was one of the main conclusions of the first day of Encuentro Amafore 2026, where national and international specialists agreed that the future of pension systems will depend on their ability to adapt to a reality in which living longer will be increasingly common, yet also more costly from a financial standpoint.
The challenge takes on particular relevance for Mexico, where the Retirement Savings System (SAR) already manages more than 9.3T pesos (around $509B), an asset pool that represents an opportunity to strengthen pensions, expand financing for productive projects, and contribute to economic growth, always under criteria of profitability, security, and fiduciary responsibility.
The discussion began with a warning about what could become humanity’s next major revolution. David Sinclair, a Harvard scientist specializing in longevity, anticipated that following artificial intelligence, the next major shift will be tied to extending healthy lifespans, driven by scientific and technological advances.
The consequence extends far beyond medicine: if people live longer and retain their physical and intellectual capacities for more years, they will also have to modify their career, financial, and wealth decisions. In other words, retirement systems designed for a shorter life expectancy will have to respond to a completely different reality.
The problem, therefore, is not limited to getting workers to accumulate more money during their working lives. It will also be necessary to ensure that those resources last to finance a retirement that could span several decades. Matthew Michelini, President of Athene, placed the emphasis precisely on that transition: pension systems must stop treating accumulation and decumulation as independent processes.
His proposition is that investment strategies must factor in from the outset how savings will be transformed into income during retirement. “Accumulation and decumulation strategies have to be combined,” he argued, warning that the true challenge lies in designing solutions that allow pension wealth to be converted into a sufficient and sustainable source of income.
Yet before thinking about how to spend accumulated resources, another obstacle stands in the way: keeping them invested for the necessary duration. David Laibson, behavioral economist and Harvard professor, pointed out that mechanisms such as automatic enrollment and automatic contributions help foster saving, though they lose effectiveness when workers make early withdrawals or face immediate financial needs.
For Mexico, the specialist deemed it necessary to develop instruments that protect long-term savings and allow informal workers to be brought into the fold. To that end, digital payment platforms could become a tool to broaden participation and facilitate contributions to the pension system.
From retirement savings to productive investment
The other major discussion of the gathering centered on the destination of pension assets and their capacity to become an investment lever for the country.
With more than 9.3T pesos under management, the SAR represents one of Mexico’s largest pools of institutional savings. María del Carmen Bonilla Rodríguez, Undersecretary of Finance, highlighted that an opportunity exists to channel a greater proportion of those assets toward productive projects, provided they feature legal certainty, technical viability, and attractive returns for workers.
The official put a fundamental principle on the table: economic development and pension sustainability must not be understood as opposing objectives. However, for both to advance, Afore participation must preserve the administrators’ fiduciary responsibility, as well as establish appropriate risk-sharing frameworks.
The discussion is particularly relevant because the growth of pension assets requires finding new investment opportunities without sacrificing the return and security objectives that must prevail in managing workers’ resources.
Against this backdrop, artificial intelligence is beginning to reshape the opportunity map for institutional investors. Reid Menge, Co-Portfolio Manager of Global Technology at BlackRock, explained that this revolution is driving investments in compute infrastructure, energy, data centers, robotics, and healthcare.
Nevertheless, he warned that energy availability could become one of the main bottlenecks to sustaining technological expansion. This means the race to capitalize on artificial intelligence will not be limited to companies developing models and applications, but will also involve the sectors capable of providing the infrastructure necessary for its operation.
Technological transformation compounds other factors reshaping investment decisions: economic fragmentation, geopolitical tensions, and market concentration. Specialists from CME Group, Barclays, Janus Henderson, and Veritas agreed that this environment compels investors to review their diversification strategies across regions, sectors, and asset classes.
Rob Lovelace, President of Capital International and portfolio manager at Capital Group, warned that market concentration reinforces the importance of maintaining a long-term perspective and active management capable of distinguishing between sustainable opportunities and cyclical swings.
For pension funds, whose investment horizon can span several decades, avoiding hasty decisions in the face of volatility episodes will be decisive in protecting return targets.
Financial infrastructure also enters the equation
Market modernization constitutes another element of the pension agenda. Jorge Alegría, CEO of Grupo BMV, highlighted progress in strengthening clearing and settlement processes in Mexico’s bond market, while Tannia Munroe of Tradeweb underscored that electronic trading and central clearing can help improve liquidity and reduce operating costs.
The international discussion also reached the political arena. David Agnew, Managing Director at Macquarie Group, noted that the results of the U.S. midterm elections will carry implications for investment decisions, particularly in sectors such as energy, infrastructure, and data centers, where state government policies and regulations can prove decisive.
On the pension front, the overarching assessment was that Mexico possesses a well-positioned system, yet still faces significant pending tasks regarding pension coverage and adequacy.
During the panel The Future of Pensions: A Global Perspective, Amy Barklam, His Majesty’s Trade Commissioner for Latin America and the Caribbean, maintained that reforms must be evaluated by the outcomes they generate for savers and not solely by the regulatory changes they introduce.
For his part, André Maxnuk, CEO of Marsh México, recognized the strength of the Mexican system in terms of sustainability and funding, though he identified coverage as one of the areas where room for improvement remains.
In parallel, the event’s agenda incorporated a gender perspective within the financial industry. The Interinstitutional Committee for Gender Equality in Financial Entities presented advances in narrowing gaps, increasing female participation in executive roles, and building safe workplaces.
During the meeting, Finance Secretary Édgar Amador Zamora called for extending these efforts nationwide. The body also announced a permanent collaboration with UN Women and the handover of its presidency, which will be assumed by Amafore over the coming year following the term led by Amsofipo.
The takeaway from the first day of Encuentro Amafore 2026 leaves a conclusion that transcends fund administrators and financial markets: the future of pensions will depend on more than increasing individual account balances. It will be necessary to expand the saver base, prevent resources from being withdrawn prematurely, diversify investments, and build mechanisms capable of financing a longer retirement.
The SAR’s 9.3T pesos represent an extraordinary opportunity for Mexico, yet also a responsibility of enormous proportions. The challenge will be ensuring that this wealth generates returns for workers, finances productive activities, and contributes to national development without losing sight of its fundamental purpose: guaranteeing better living conditions during retirement.
Because if longevity is changing the meaning of retirement, pensions will have to change as well. Reaching retirement with accumulated money will no longer suffice; that money will have to be made to last as long as the life it must finance.
Photo courtesyStefan Kuhn, Head of ETF Distribution for EMEA at Fidelity International.
ETFs are experiencing strong growth, and the trend is set to continue. According to Fidelity International’s latest survey, European professional investors are preparing to increase their allocations to active exchange-traded funds. Specifically, average allocations to active ETFs are projected to rise from the current 10.2% of portfolios to 14.6% over the next 18 months. Against this backdrop, Stefan Kuhn, Head of ETF Distribution for EMEA at Fidelity International, breaks down the trends and challenges surrounding these vehicles, including a growing tilt toward more index-oriented solutions as well as longevity and retirement planning.
ETFs have experienced a genuine boom in Europe in recent years. What factors will help sustain this trend in the near future?
More and more savers are taking the step to become investors. Issues such as longevity and retirement planning occupy a central place in conversations with end clients today, and ETFs have established themselves as one of the preferred options for those starting to invest. At the same time, there is a growing tilt toward more index-oriented solutions for certain parts of portfolios. There remains ample room for actively managed funds, but combining high-conviction active strategies with more indexed solutions is gaining increasing prominence.
In general terms, what trends are you observing in the European ETF industry?
Without a doubt, we are seeing a clear trend toward active ETF solutions. It remains to be seen whether demand will concentrate primarily on strategies with a stronger index orientation or whether it will eventually shift toward genuinely active funds packaged in an ETF format. In my view, the former makes more sense, as an ETF is not just an investment vehicle or format, but almost a philosophy. Cost-efficient, index-oriented, and systematically managed solutions packaged inside an ETF appear to be precisely what the market demands.
Which European countries are recording the strongest ETF growth?
The main ETF markets in Europe are the United Kingdom, Germany, Italy, and Switzerland, although France and the Nordic countries are also gaining ground rapidly. In Spain, the transfer regime poses a certain obstacle, as the tax treatment of traditional unlisted mutual funds, including index funds, is more favorable than that of ETFs. Were this situation to change, there is significant latent demand that could drive the growth of the Spanish market.
What lessons can Europe learn from the United States to continue driving ETF growth?
One of the main lessons is the naturalness with which the debate around retirement and the potential retirement savings gap is approached. In the United States, people talk much more openly about how they invest for retirement than in Europe. Although Europeans are aware that they will likely need to save more to supplement their retirement, these conversations are not as widespread as across the Atlantic. It is also worth noting that ETFs in the United States enjoy a significant tax advantage over traditional mutual funds, which is not the case in Europe. Even so, the appeal of more index-oriented solutions within the ETF format is a reality across the continent.
What would you advise an investor who does not yet hold ETFs in their portfolio, but is considering adding them over the short or medium term?
Over the short term, broad exposure to global equities is probably the most logical first step. That exposure can be obtained through either an active or a passive ETF. Maintaining an equity allocation remains, over the long term, one of the best ways to preserve purchasing power against inflation. Over a more medium-term horizon, active ETFs prove particularly attractive. It is not merely about replicating the market, but about benefiting from the contribution of an active manager seeking to generate additional value relative to the index.
Which ETF strategies currently offer the best opportunities?
For the retail investor, the greatest opportunities remain in U.S. and global equity exposures. For professional investors, opportunities tend to lie in more specialized or niche strategies. In my opinion, end investors should not overcomplicate their portfolio construction. If they manage their investments on their own, the most important thing is to be invested in the market. For those who have or are willing to seek financial advice, portfolio construction takes on even greater relevance, as professional investors have access to a much broader toolkit and set of strategies.
Also noteworthy is the growth of outcome-oriented ETFs, whether focused on income generation or strategies featuring partial downside protection mechanisms.
Does the rise of active ETFs make index funds less attractive?
In Spain, I fear the decisive factor remains taxation rather than performance itself. Beyond the tax disadvantage that ETFs currently face in the Spanish market, I consider active ETFs to be considerably more attractive than passive ones.
What are Fidelity International’s goals in the ETF business, for example in terms of inflows, assets under management, or entry into new markets?
As our Head of EMEA, Samantha Ricciardi, has noted, our objective is to more than triple current assets under management to reach €60B over the coming years. Furthermore, we aspire to remain among the 3 largest providers of active ETFs both in Europe and globally.
Jupiter Asset Management has announced the appointment of William Lopez and Selina Tyler as Co-Heads of its Client Group, effective January 1, 2027. According to the asset manager, Selina joined Jupiter in the spring of 2025 as Head of UK and has since restructured and revitalized the British team, while strengthening and developing key strategic client relationships. Selina will continue leading the UK market—Jupiter’s largest business—and will also assume leadership of the Client Experience and Market Intelligence teams.
Meanwhile, William joined Jupiter in 2018, initially assuming responsibility for the Latin America business and subsequently for Iberia, before also taking over oversight of broader European markets last year. Both have made a significant impact on Jupiter’s market presence and in driving the turnaround currently evident across the firm. Furthermore, William will focus on the higher-growth businesses outside the UK (Europe, Asia, and the Americas) and will also lead Jupiter’s Institutional and Client Solutions teams.
In addition to these 2 changes, Jupiter also announces that Maximilian Guenzl will transition into the newly created role of Chief Strategy Officer. Max has completed 3 successful years at the helm of the Client Group, transforming how Jupiter engages with its clients and fostering the positive momentum currently seen across the entire firm. According to the firm, in this new position, Guenzl will leverage his deep understanding of Jupiter’s clients and their evolving needs to ensure the Group is strategically positioned to deliver its active management expertise to a broader client base. Moreover, he will help define and drive the Group’s strategic agenda, identifying organic and inorganic growth opportunities in a rapidly transforming environment.
Regarding these changes, Matthew Beesley, CEO of Jupiter AM, commented: “I am delighted that Selina and William are becoming Co-Heads of Jupiter’s Client Group. Both have made a real difference to the firm since joining, and their complementary experience and expertise place them in an ideal position to continue building on our positive momentum. During his 3 years leading the Client Group, Max has been instrumental in generating this momentum. Under his leadership, a transformative shift has taken place in how we engage with our clients, deepening relationships and expanding the reach of our active investment expertise. In this new phase, his insight into the rapidly evolving needs of our clients will be decisive in ensuring we are best positioned to capture the opportunities ahead.”
Following the CCLA transaction
Furthermore, Jupiter communicates that, having led the CCLA transaction and played a pivotal role in driving its integration, Peter Hugh Smith, Chief Executive Officer of CCLA, and Elizabeth Sheldon, Chief Operating Officer of CCLA, will step down from their respective roles. Peter and Liz joined CCLA in 2019 and 2011, respectively, and have overseen a period of solid growth, reshaping the entity’s operating model during a time of profound industry change.
Consequently, Andrew Robinson MBE will be appointed Executive Chair of CCLA. Since joining in 2006, Andrew has been the driving force behind CCLA’s consolidation across the UK non-profit and local authority sectors. In his new role, he will play a key part as the public face of CCLA.
“Andrew has been the visionary and architect behind CCLA’s extraordinary growth since his arrival in 2006. Thanks to his work, CCLA is recognized today as one of the leading asset managers in the UK non-profit and local authority sectors. Both Peter and Liz have been central to CCLA’s success in recent years and have played an essential role in the acquisition and integration process. Personally, I owe them a debt of gratitude for their commitment and support over the past 18 months,” Beesley added.
Exchange-traded funds (ETFs) are on track to set record levels for both product launches and liquidations. Steady asset expansion and accelerating institutional adoption are prompting issuers to bring new strategies to market, but the proliferation of product lineups has intensified competition for assets under management, distribution shelf space, and internal capital. Consequently, ETF sponsors must determine not only which products to launch, but also which strategies warrant ongoing investment, according to “The Cerulli Report—U.S. Exchange-Traded Fund Markets 2026.”
During the first half of 2026, the industry rolled out 733 ETFs and liquidated 145, placing both metrics on pace to rival or surpass recent historical highs. Against this backdrop, product rationalization is becoming an essential operational discipline as sponsors evaluate which strategies demonstrate sufficient commercial viability to justify continued capital allocation.
According to Cerulli, 65% of ETF issuers identify balancing product development versus product rationalization as one of their primary operational concerns. Shifting investor demand and product differentiation follow at 61%, ranking ahead of market volatility and macroeconomic uncertainty at 35%.
When deciding which products to sunset, sponsors place the greatest weight on commercial viability. An overwhelming 88% of issuers cite insufficient asset growth as a key driver of liquidation decisions, while 69% point to inadequate demand from core distribution partners.
In contrast, 38% point to underperformance of the underlying investment strategy. These findings demonstrate that an ETF does not necessarily have to fail from an investment performance standpoint to face closure; it becomes equally vulnerable when it fails to build a credible asset gathering trajectory or secure distribution support.
“Early adoption, asset growth, and differentiated products can indicate an ETF with upside potential, but they do not guarantee sustained commercial viability,” states Kevin Lyons, Associate Director. “Both market conditions and allocator preferences can pivot rapidly, requiring ETF sponsors to continuously monitor their lineups across multiple operational fronts, including organic asset growth, absolute and relative performance, competitive fee positioning, distribution momentum, and client demand,” he notes.
Cerulli recommends that ETF lineup rationalization should not be viewed merely as the terminal phase of an unsuccessful strategy. “Product rationalization is a required discipline that enables sponsors to build more focused and commercially sustainable lineups,” notes Lyons, adding that the most successful asset managers “will not be defined by the gross quantity of ETFs on their platform, but by their capability to isolate strategies backed by authentic client demand and distribution access, act decisively when that viability erodes, and redeploy internal resources toward future growth drivers.”
Global X announced the launch of the Global X Magnificent Six ETF (SIX), which aims to deliver exposure to the “Magnificent Six,” a cohort of technology and growth leaders currently comprising Alphabet, Amazon.com, Apple, Meta Platforms, Microsoft Corporation, and NVIDIA. The fund lists on the Cboe BZX exchange.
As an actively managed fund, SIX seeks capital appreciation through economic exposure to the companies comprising the group known as the “Magnificent Six”. Under normal market conditions, the fund invests at least 80% of its net assets, plus the amount of any borrowings for investment purposes, in securities of the “Magnificent Six” and in financial instruments and other investments providing exposure to them or collectively exhibiting economic characteristics substantially similar or equivalent to those of the “Magnificent Six” companies.
The ETF expects to gain economic exposure through swap agreements and other derivative instruments, and may also directly hold common stock of the “Magnificent Six” companies. The adviser seeks to weight the fund’s exposure by free-float market capitalization.
“These 6 companies have been a significant contributor to recent U.S. earnings growth,” said Pedro Palandrani, Head of Product Research & Development at Global X. “During the 12 months ended September 30, 2026, they contributed nearly 2/3—approximately 66%—of the earnings-per-share growth of the Bloomberg 500 Index over the trailing 12 months. Furthermore, based on current estimates, these 6 companies could invest approximately $700B in capital expenditures in 2026 and $1T in 2027, with much of that spending expected to go toward AI,” he noted.
Palandrani pointed out that the group’s combined capital expenditure positions these companies among the largest builders of AI infrastructure. “The scale of these 6 companies may enable them to reinvest at a pace few companies can match, which could help support their long-term earnings generation capacity,” he added.
Global X operates more than 30 thematic ETFs designed to invest in companies driving disruptive innovation and structural change. The lineup spans strategies ranging from infrastructure development and electrification to robotics, cybersecurity, and data centers. SIX, alongside 4 other recently launched ETFs, aims to provide allocators with targeted exposure to specialized technological and innovation segments through a single ETF vehicle.
Following the November 2026 U.S. midterm elections, the price of gold recorded a sharp bullish rebound, marking its best weekly performance in several months and reclaiming the psychological threshold of $4,000 per ounce. “Gold stabilized to some extent on Wednesday following Tuesday’s losses. The metal continues to find support in sustained demand from central banks. These collectively purchased 321 tons during Q3, extending an aggressive official-sector buying pattern. Robust demand could help contain any selling wave across the gold market,” notes Tim Furey, founder and CEO of Tradeview Markets & YimmiT, regarding its performance.
Taking the U.S. midterm elections as a benchmark, spot gold surged more than 3.4% in a single day during the post-election session, marking its largest daily advance since mid-August. “The metal moved from testing late-October lows near $3,870 to clearing $4,060 – $4,150 per ounce in the sessions following the vote, consolidating a weekly gain near 5%,” indicates Furey.
Catalysts behind the rally
Market experts identify the legislative gridlock produced by the election outcome as a primary catalyst for this rally. “This divided government backdrop typically narrows the runway for aggressive expansionary fiscal measures, unilateral tax cuts, or outsized debt ceiling increases, which curtailed expectations of expanding public debt,” notes Franklin Templeton.
A second driver was the pullback in Treasury yields. In this regard, expectations of reduced fiscal pressure and spending restraint exerted downward pressure on U.S. sovereign debt yields. This lowered the opportunity cost of holding non-yielding assets, directly benefiting bullion.
Lastly, analysts point toward an easing of geopolitical risk. Post-election signals indicated a lower probability of abrupt near-term trade or military escalations, mitigating pressure on energy commodities such as crude oil and dampening inflation concerns that might otherwise compel the Federal Reserve (Fed) to tighten monetary policy further.
Outlook for gold
When assessing the trajectory for gold, the $4,000 level has established itself as the critical support benchmark. “Our projections for gold indicate prices approaching $4,800 per ounce by Q3 2027. We expect this recovery to support silver given its precious metal characteristics and investment demand. However, industrial weakness will likely temper silver’s participation in this advance,” states Nitesh Shah, Head of Commodities and Investment Strategists at WisdomTree.
For Ned Naylor-Leyland, gold and silver fund manager at Jupiter AM, the structural case for gold—and silver—remains intact. He explains that “the secular trend toward fiat currency debasement relative to gold, expanding central bank balance sheets, and de-dollarization is deeply entrenched and persistent. Rather than viewing gold as a productive asset, I regard it as a risk-free monetary unit that preserves purchasing power as fiat currencies depreciate over time.”
US exceptionalism has shaped portfolios as much as it has shaped market expectations. After more than a decade of US leadership, our starting point is to question whether the conditions behind past market leadership still hold.
We think a more revealing question is what made the previous decade so unusual. The years following the Global Financial Crisis combined exceptionally low interest rates, a strengthening dollar and powerful growth in a narrow group of US businesses. As those conditions change, we see a global opportunity set that deserves a fresh look. Do portfolios built around yesterday’s winners fully reflect where tomorrow’s earnings and returns may come from?
When market size outpaces fundamentals
The success of leading US companies is undeniable. Yet the scale of US market dominance tells us more than the strength of those businesses alone.
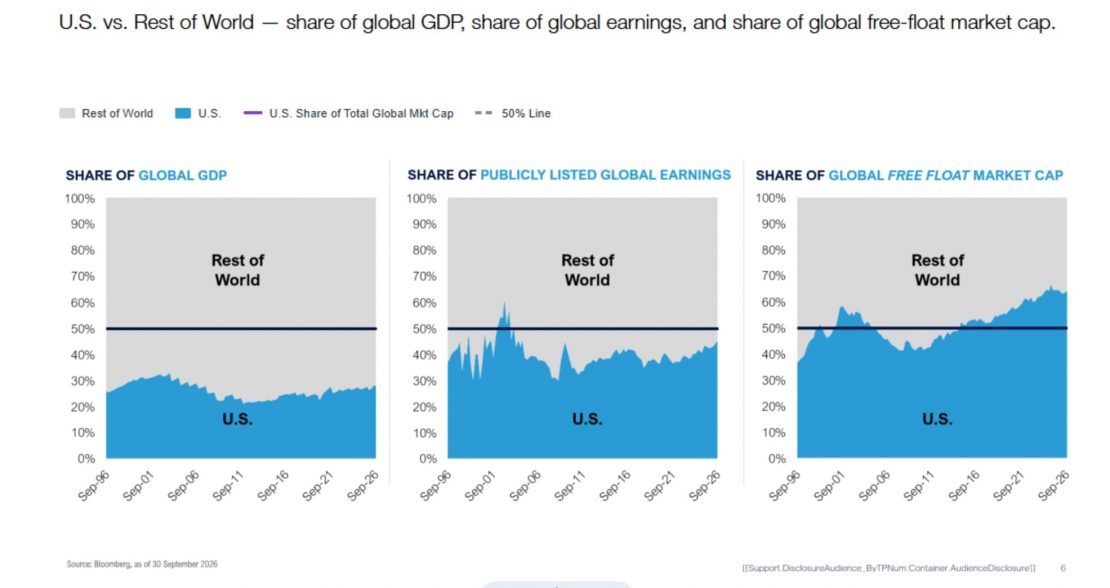
Over three decades, the US share of global GDP and listed company earnings has changed relatively little. Its share of global equity market capitalisation, however, has risen substantially since the financial crisis. Share prices have become more exceptional than the underlying economic proportions.
One comparison brings that concentration into focus: at mid-2026, the Magnificent Seven’s combined market capitalisation exceeded the value of the entire MSCI US Index in 2016.
For us, this raises a portfolio question. How much future return depends on a small group of companies continuing to meet increasingly demanding expectations? And what opportunities might be overlooked elsewhere?
Growth has a wider address
Technology remains an important source of earnings growth. But it is far from the only one.
We see earnings strengthening across sectors outside the US, creating opportunities in businesses that receive less attention than the dominant market leaders. A more normal cost of capital is helping reshape that landscape.
Positive interest rates have improved lending economics for financial companies in many international markets. Healthier financial sectors can support businesses seeking capital to expand. Recovering labour markets and continued growth in global trade also challenge the assumption that international companies’ fortunes revolve around US demand.
These changes make the research question more interesting. Which businesses can turn improving conditions into durable earnings? Which have the competitive strengths to sustain them? And how much of that potential is already reflected in the price?
A strong business still needs the right price
An attractive growth story can become a demanding investment when expectations run ahead of fundamentals.
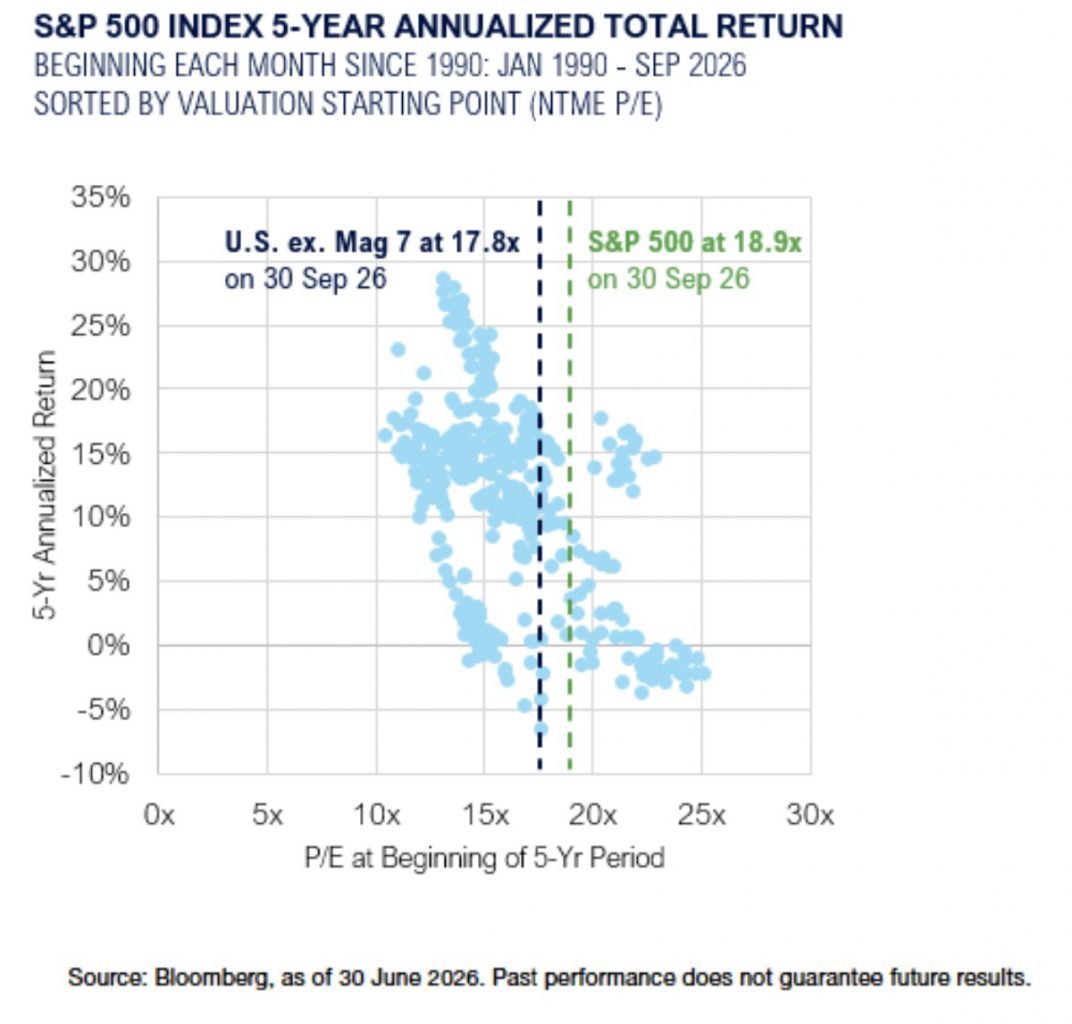
Our historical analysis shows that higher starting valuations for US equities have been associated with a less favourable range of subsequent five-year returns. Valuation cannot tell us when leadership will change, but it helps us judge what must go right to justify the price.
Currency matters too. Dollar strength supported US assets’ relative performance during much of the previous decade. A stabilising or weakening dollar could ease a longstanding headwind for international equities held by dollar-based investors.
Higher dividend yields outside the US offer another potential contribution to total return. We examine the cash flows supporting those payments, rather than treating yield alone as evidence of value.
Bring the opportunity into the portfolio
Our global generalist research model brings a broader perspective to security selection. We compare businesses across sectors and countries, challenging assumptions and weighing quality, valuation and portfolio contribution together. Every potential holding must compete for capital against the team’s strongest ideas.
That discipline takes distinct forms across three UCITS strategies. Equity Income Builder seeks companies with durable cash flows and the ability to sustain and grow dividends. Global Opportunities builds a concentrated, high-conviction portfolio unconstrained by benchmark weights. International Equity applies our Three-Basket framework to opportunities outside the US.
Each strategy offers a distinct way to put that broader perspective to work. Our generalist approach keeps us open to opportunities wherever they emerge—including in the US—with conviction grounded in research and valuation rather than past market leadership.
Opinion column written by Josh Rubin, Client Portfolio Manager at Thornburg.
Explore the evidence behind our broader perspective in “Back to Normal” in Global Equities.