US exceptionalism has shaped portfolios as much as it has shaped market expectations. After more than a decade of US leadership, our starting point is to question whether the conditions behind past market leadership still hold.
We think a more revealing question is what made the previous decade so unusual. The years following the Global Financial Crisis combined exceptionally low interest rates, a strengthening dollar and powerful growth in a narrow group of US businesses. As those conditions change, we see a global opportunity set that deserves a fresh look. Do portfolios built around yesterday’s winners fully reflect where tomorrow’s earnings and returns may come from?
When market size outpaces fundamentals
The success of leading US companies is undeniable. Yet the scale of US market dominance tells us more than the strength of those businesses alone.
Over three decades, the US share of global GDP and listed company earnings has changed relatively little. Its share of global equity market capitalisation, however, has risen substantially since the financial crisis. Share prices have become more exceptional than the underlying economic proportions.
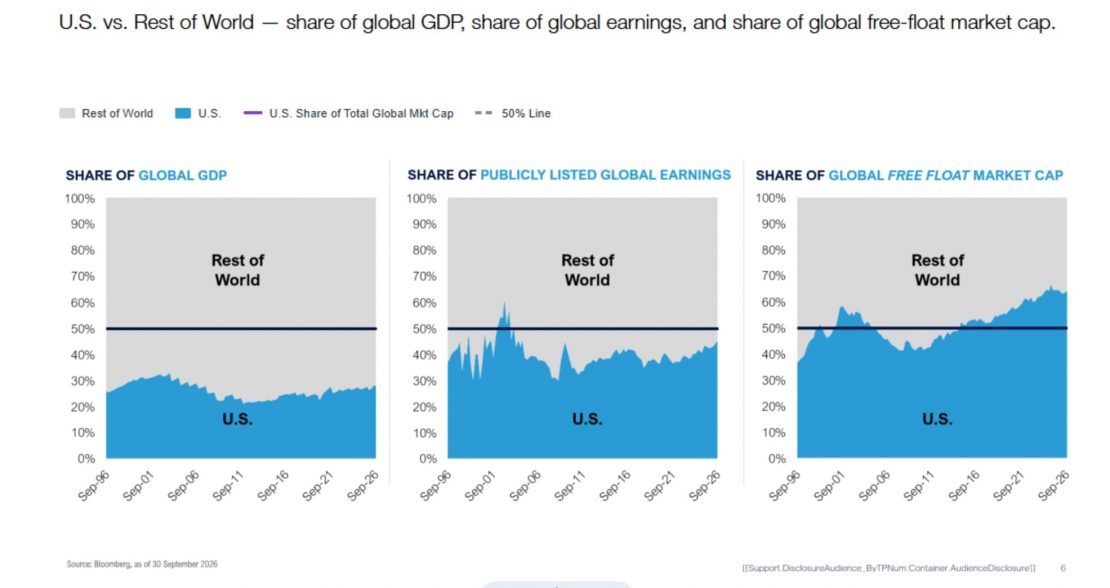
One comparison brings that concentration into focus: at mid-2026, the Magnificent Seven’s combined market capitalisation exceeded the value of the entire MSCI US Index in 2016.
For us, this raises a portfolio question. How much future return depends on a small group of companies continuing to meet increasingly demanding expectations? And what opportunities might be overlooked elsewhere?
Growth has a wider address
Technology remains an important source of earnings growth. But it is far from the only one.
We see earnings strengthening across sectors outside the US, creating opportunities in businesses that receive less attention than the dominant market leaders. A more normal cost of capital is helping reshape that landscape.
Positive interest rates have improved lending economics for financial companies in many international markets. Healthier financial sectors can support businesses seeking capital to expand. Recovering labour markets and continued growth in global trade also challenge the assumption that international companies’ fortunes revolve around US demand.
These changes make the research question more interesting. Which businesses can turn improving conditions into durable earnings? Which have the competitive strengths to sustain them? And how much of that potential is already reflected in the price?
A strong business still needs the right price
An attractive growth story can become a demanding investment when expectations run ahead of fundamentals.
Our historical analysis shows that higher starting valuations for US equities have been associated with a less favourable range of subsequent five-year returns. Valuation cannot tell us when leadership will change, but it helps us judge what must go right to justify the price.
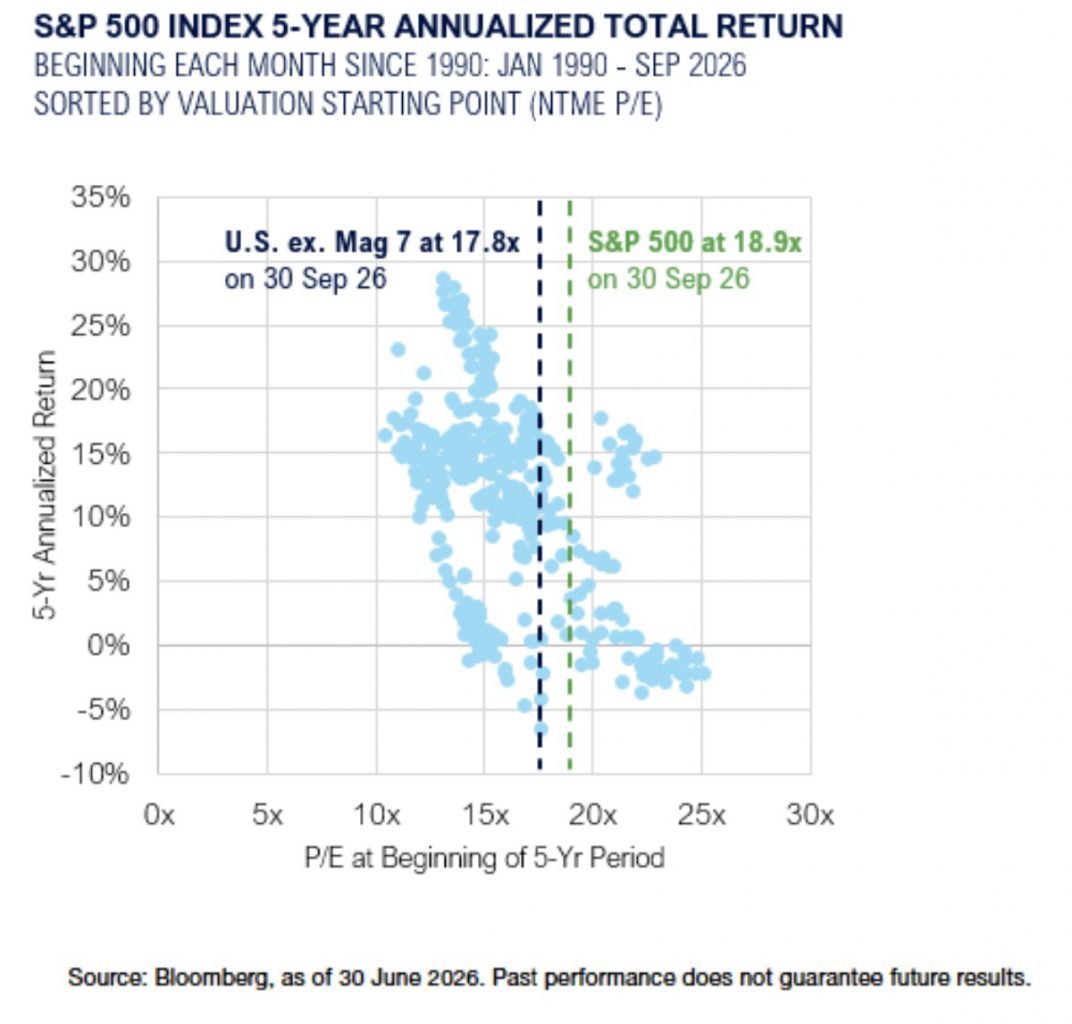
Currency matters too. Dollar strength supported US assets’ relative performance during much of the previous decade. A stabilising or weakening dollar could ease a longstanding headwind for international equities held by dollar-based investors.
Higher dividend yields outside the US offer another potential contribution to total return. We examine the cash flows supporting those payments, rather than treating yield alone as evidence of value.
Bring the opportunity into the portfolio
Our global generalist research model brings a broader perspective to security selection. We compare businesses across sectors and countries, challenging assumptions and weighing quality, valuation and portfolio contribution together. Every potential holding must compete for capital against the team’s strongest ideas.
That discipline takes distinct forms across three UCITS strategies. Equity Income Builder seeks companies with durable cash flows and the ability to sustain and grow dividends. Global Opportunities builds a concentrated, high-conviction portfolio unconstrained by benchmark weights. International Equity applies our Three-Basket framework to opportunities outside the US.
Each strategy offers a distinct way to put that broader perspective to work. Our generalist approach keeps us open to opportunities wherever they emerge—including in the US—with conviction grounded in research and valuation rather than past market leadership.
Opinion column written by Josh Rubin, Client Portfolio Manager at Thornburg
This material is for investment professionals and institutional investors only.
Important Information
This is a marketing communication
Investments carry risks, including possible loss of principal. Additional risks may be associated with investments in emerging markets, including currency fluctuations, illiquidity, volatility, and political and economic risks. Investments in small- and mid-capitalization companies may increase the risk of greater price fluctuations. Portfolios investing in bonds have the same interest rate, inflation, and credit risks that are associated with the underlying bonds. The value of bonds will fluctuate relative to changes in interest rates, decreasing when interest rates rise. Unlike bonds, bond funds have ongoing fees and expenses. Investments in mortgage-backed securities (MBS) may bear additional risk. Investments in the Fund are not insured, nor are they bank deposits or guaranteed by a bank or any other entity. For risks materially relevant to the Fund, please read the Fund’s Annual Report or Prospectus/Supplement available at www.thornburg.com/ucits.
This does not constitute or contain an offer, solicitation, recommendation or investment advice with respect to the purchase of the Funds described herein or any security. The Fund’s shares may not be sold to citizens or residents of the United States or in any other state, country, or jurisdiction where it would be unlawful to offer, solicit an offer for, or sell the shares. For information regarding the jurisdictions in which the Fund is registered or passported, please contact Thornburg at global@thornburg.com or +1.855.732.9301. Fund shares may be sold on a private placement basis depending on the jurisdiction. This should not be used or distributed in any jurisdiction, other than in those in which the Fund is authorized, where authorization for distribution is required. Thornburg is authorized by the Fund to facilitate the distribution of shares of the Fund in certain jurisdictions through dealers, referral agents, sub-distributors and other financial intermediaries. Any entity forwarding this, which is produced by Thornburg in the United States, to other parties takes full responsibility for ensuring compliance with applicable securities laws in connection with its distribution.
The Fund is a sub-fund of Thornburg Global Investment plc (“TGI”), an open-ended investment company with variable capital constituted as an umbrella fund with segregated liability between sub-funds, authorized and regulated by the Central Bank of Ireland (“CBI”) as an Undertaking for Collective Investments in Transferable Securities (“UCITS”). Authorization of TGI by the CBI is not an endorsement or guarantee by the CBI nor is the CBI responsible for the contents of any marketing material or the Fund’s prospectus, supplement or applicable Key Information Document (“KID”). Authorization by the CBI shall not constitute a warranty as to the performance of TGI and the CBI shall not be liable for the performance of TGI.
Before investing, investors should review the Fund’s full prospectus and supplement, together with the applicable KID and the most recent annual and semi-annual reports.
Copies of the Fund’s prospectus and supplement can be obtained from State Street Fund Services (Ireland) Limited, by visiting www.thornburg.com/ucits or by contacting the local paying or representative agent or local distributor in the jurisdictions in which the Fund is available for distribution, and are available in English.
The KIDs can be obtained from www.thornburg.com/ucits and are available in one of the official languages of each of the EU Member States into which the Fund has been notified for marketing under the Directive 2009/65/EC (the UCITS Directive).
In addition, a summary of investor rights is available from www.thornburg.com/ucits. The summary is available in English.
The Fund is currently notified for marketing into a number of EU Member States under the UCITS Directive. The Fund can terminate such notifications for any share class and/or the Fund at any time using the process contained in Article 93a of the UCITS Directive.
No securities commission or regulatory authority has in any way passed upon the merits of an investment in the Fund or the accuracy or adequacy of this information or the material contained herein or otherwise. Neither this or the Offering Documents have been approved in any jurisdiction where the Fund has not been registered for public offer and sale. This information is not, and under no circumstances is to be construed as the Offering Documents, a public offering or an offering memorandum as defined under applicable securities legislation. Application for shares may only be made by way of the Fund’s most recent Offering Documents.
The Fund is actively managed and is not constrained by any benchmark.
The Fund is actively managed and is not constrained by any benchmark.
For Argentina, Bolivia, Brazil, Chile, Mexico, Peru, Uruguay: This material is for informational purposes and is intended only for Investment Professionals, as that term is defined in each jurisdiction. This information relates to a foreign Fund which is not subject to any form of local regulation or licensing. No regulator, government authority, or other entities are responsible for reviewing or verifying, and have not reviewed or verified, this information, the merits of the Fund or services represented, the offering documents, or any other documents in connection with this Fund. Interests may not be offered or sold to the public and documents relating to this Fund (as well as the information contained herein) may not be supplied to the general public for purposes of a public offering or be used in connection with any offer or subscription for sale to the public.