The pension industry is facing a paradigm shift: longevity, labor market transformation, and the technological revolution are forcing a rethink not only of how much workers must save, but also of how their assets are invested and, above all, how they are converted into income capable of sustaining them through longer retirement periods.
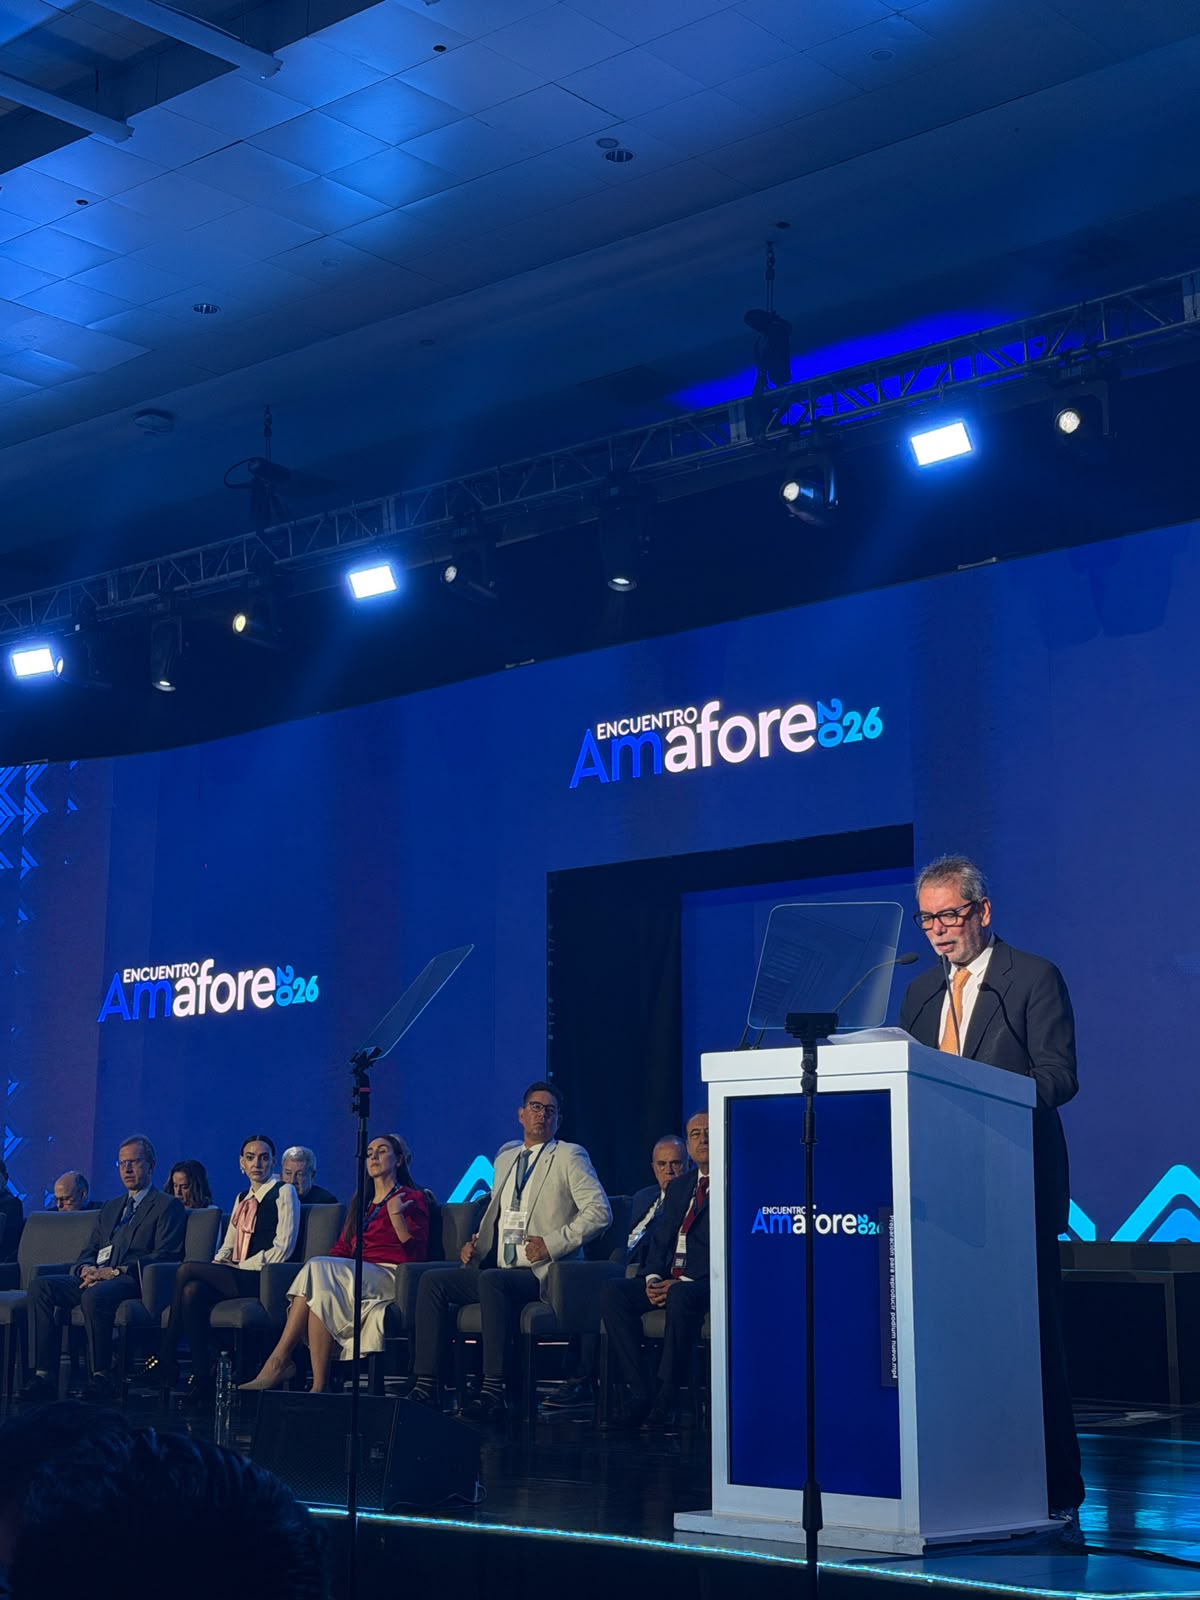
That was one of the main conclusions of the first day of Encuentro Amafore 2026, where national and international specialists agreed that the future of pension systems will depend on their ability to adapt to a reality in which living longer will be increasingly common, yet also more costly from a financial standpoint.
The challenge takes on particular relevance for Mexico, where the Retirement Savings System (SAR) already manages more than 9.3T pesos (around $509B), an asset pool that represents an opportunity to strengthen pensions, expand financing for productive projects, and contribute to economic growth, always under criteria of profitability, security, and fiduciary responsibility.
The discussion began with a warning about what could become humanity’s next major revolution. David Sinclair, a Harvard scientist specializing in longevity, anticipated that following artificial intelligence, the next major shift will be tied to extending healthy lifespans, driven by scientific and technological advances.
The consequence extends far beyond medicine: if people live longer and retain their physical and intellectual capacities for more years, they will also have to modify their career, financial, and wealth decisions. In other words, retirement systems designed for a shorter life expectancy will have to respond to a completely different reality.
The problem, therefore, is not limited to getting workers to accumulate more money during their working lives. It will also be necessary to ensure that those resources last to finance a retirement that could span several decades. Matthew Michelini, President of Athene, placed the emphasis precisely on that transition: pension systems must stop treating accumulation and decumulation as independent processes.
His proposition is that investment strategies must factor in from the outset how savings will be transformed into income during retirement. “Accumulation and decumulation strategies have to be combined,” he argued, warning that the true challenge lies in designing solutions that allow pension wealth to be converted into a sufficient and sustainable source of income.
Yet before thinking about how to spend accumulated resources, another obstacle stands in the way: keeping them invested for the necessary duration. David Laibson, behavioral economist and Harvard professor, pointed out that mechanisms such as automatic enrollment and automatic contributions help foster saving, though they lose effectiveness when workers make early withdrawals or face immediate financial needs.
For Mexico, the specialist deemed it necessary to develop instruments that protect long-term savings and allow informal workers to be brought into the fold. To that end, digital payment platforms could become a tool to broaden participation and facilitate contributions to the pension system.
From retirement savings to productive investment
The other major discussion of the gathering centered on the destination of pension assets and their capacity to become an investment lever for the country.
With more than 9.3T pesos under management, the SAR represents one of Mexico’s largest pools of institutional savings. María del Carmen Bonilla Rodríguez, Undersecretary of Finance, highlighted that an opportunity exists to channel a greater proportion of those assets toward productive projects, provided they feature legal certainty, technical viability, and attractive returns for workers.
The official put a fundamental principle on the table: economic development and pension sustainability must not be understood as opposing objectives. However, for both to advance, Afore participation must preserve the administrators’ fiduciary responsibility, as well as establish appropriate risk-sharing frameworks.
The discussion is particularly relevant because the growth of pension assets requires finding new investment opportunities without sacrificing the return and security objectives that must prevail in managing workers’ resources.
Against this backdrop, artificial intelligence is beginning to reshape the opportunity map for institutional investors. Reid Menge, Co-Portfolio Manager of Global Technology at BlackRock, explained that this revolution is driving investments in compute infrastructure, energy, data centers, robotics, and healthcare.
Nevertheless, he warned that energy availability could become one of the main bottlenecks to sustaining technological expansion. This means the race to capitalize on artificial intelligence will not be limited to companies developing models and applications, but will also involve the sectors capable of providing the infrastructure necessary for its operation.
Technological transformation compounds other factors reshaping investment decisions: economic fragmentation, geopolitical tensions, and market concentration. Specialists from CME Group, Barclays, Janus Henderson, and Veritas agreed that this environment compels investors to review their diversification strategies across regions, sectors, and asset classes.
Rob Lovelace, President of Capital International and portfolio manager at Capital Group, warned that market concentration reinforces the importance of maintaining a long-term perspective and active management capable of distinguishing between sustainable opportunities and cyclical swings.
For pension funds, whose investment horizon can span several decades, avoiding hasty decisions in the face of volatility episodes will be decisive in protecting return targets.
Financial infrastructure also enters the equation
Market modernization constitutes another element of the pension agenda. Jorge Alegría, CEO of Grupo BMV, highlighted progress in strengthening clearing and settlement processes in Mexico’s bond market, while Tannia Munroe of Tradeweb underscored that electronic trading and central clearing can help improve liquidity and reduce operating costs.
The international discussion also reached the political arena. David Agnew, Managing Director at Macquarie Group, noted that the results of the U.S. midterm elections will carry implications for investment decisions, particularly in sectors such as energy, infrastructure, and data centers, where state government policies and regulations can prove decisive.
On the pension front, the overarching assessment was that Mexico possesses a well-positioned system, yet still faces significant pending tasks regarding pension coverage and adequacy.
During the panel The Future of Pensions: A Global Perspective, Amy Barklam, His Majesty’s Trade Commissioner for Latin America and the Caribbean, maintained that reforms must be evaluated by the outcomes they generate for savers and not solely by the regulatory changes they introduce.
For his part, André Maxnuk, CEO of Marsh México, recognized the strength of the Mexican system in terms of sustainability and funding, though he identified coverage as one of the areas where room for improvement remains.
In parallel, the event’s agenda incorporated a gender perspective within the financial industry. The Interinstitutional Committee for Gender Equality in Financial Entities presented advances in narrowing gaps, increasing female participation in executive roles, and building safe workplaces.
During the meeting, Finance Secretary Édgar Amador Zamora called for extending these efforts nationwide. The body also announced a permanent collaboration with UN Women and the handover of its presidency, which will be assumed by Amafore over the coming year following the term led by Amsofipo.
The takeaway from the first day of Encuentro Amafore 2026 leaves a conclusion that transcends fund administrators and financial markets: the future of pensions will depend on more than increasing individual account balances. It will be necessary to expand the saver base, prevent resources from being withdrawn prematurely, diversify investments, and build mechanisms capable of financing a longer retirement.
The SAR’s 9.3T pesos represent an extraordinary opportunity for Mexico, yet also a responsibility of enormous proportions. The challenge will be ensuring that this wealth generates returns for workers, finances productive activities, and contributes to national development without losing sight of its fundamental purpose: guaranteeing better living conditions during retirement.
Because if longevity is changing the meaning of retirement, pensions will have to change as well. Reaching retirement with accumulated money will no longer suffice; that money will have to be made to last as long as the life it must finance.