U.S. Inflation in September and Implications for the Fed
| By Amaya Uriarte | 0 Comentarios
Inflation concerns continue to be the heaviest factor explaining short-term equity movements. The consensus among economists anticipated a strong U.S. inflation reading for September, which ultimately surprised on the downside: headline CPI reached +0.6%, in line with the year-over-year rate moving from 3.4% to 3.7%, while core CPI came in at +0.3% versus the +0.2% expected, shifting from 2.4% to 2.6% year-over-year. Its impact was amplified by the proximity of the Federal Reserve meeting scheduled for the 28th.
However, we believe the release was not strong enough to justify another rate hike in October. Beyond the impact of rising energy costs and the effect of AI investments on the prices of PCs, software, and mobile phones, the only aspect to monitor is the uptick in Owners’ Equivalent Rent (OER), which rose compared to the previous month.
The market’s immediate reaction to the data was to push expectations of a 25-basis-point rate hike in federal funds higher: probabilities spiked above 70%, only to quickly retreat to 12.7%, the lowest level since June. The September retail sales data (which deteriorated relative to August), the moderation in import prices shown in the Philadelphia Fed survey, and comments from Mary Daly (San Francisco Fed) and Michelle Bowman—who do not foresee a rate hike this month—exerted downward pressure on that probability, aiding the Treasury bond market. Regarding the U.S. Treasury bond, we do not believe that developments in the neocloud sector, discussed in the next section, were the main driver behind the yield compression. Investment in AI will continue to contribute positively to GDP in the coming months.
AI: Neocloud Strain and Ongoing Adoption
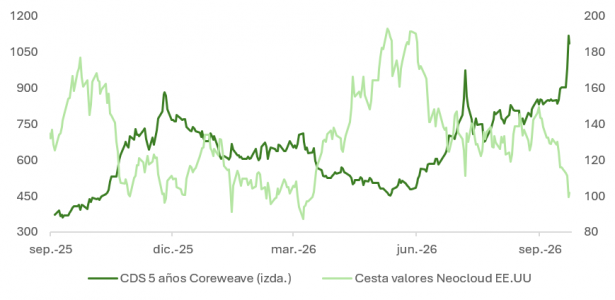
Inflation and its initial effect on the Treasury yield (which exceeded 5.32% on Wednesday before stabilizing near 5.08% on Friday) was also the catalyst for the sharp drop in share prices among neocloud companies. CoreWeave alarmed investors at the worst possible time by communicating that it would like to achieve an investment-grade credit rating to finance its growth on an “unlimited” basis. Its debt fell below 80 (against a par value of 100), having traded at par just a few months ago, while its CDS priced in a more than 50% probability of default over the next five years.
We consider this an isolated case affecting a subsegment of technology companies with higher financial leverage and greater sensitivity to rate hikes, rather than a red flag for the broader set of companies linked to the AI theme.
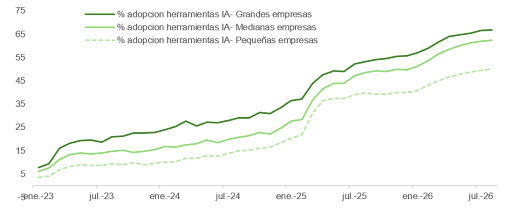
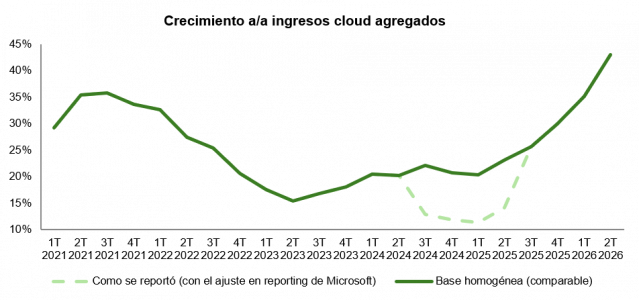
For now, the adoption of paid AI services among both large and small enterprises continues to advance, rising from 8% in large firms and less than 4% in small ones at the start of 2023 to 67% of large, 62% of mid-sized, and 50% of small businesses today—all within just three and a half years. Moreover, investments are being monetized: aggregate cloud revenues among major compute providers grew 43% year-over-year in the second quarter, based on nearly $370 billion over the last twelve months.
Geopolitics and the “Incompetence Premium” in U.S. Debt
In the short term, the evolution of inflation readings will be determined primarily by geopolitical factors. In this regard, uncertainty has heightened recently: Iran, through its Revolutionary Guard, has intensified threats against vessels that might “illegally” attempt to trade or load oil in the strait. Similarly, the Wall Street Journal reported comments from Iranian authorities regarding the deployment of troops to carry out retaliatory actions against U.S. allies in the Gulf.
As we have been explaining, one of the Iranians’ objectives is to keep the price of crude oil near $100 per barrel to minimize Trump’s chances of retaining control of the Senate as much as possible. However, the escalation in hostilities places Iran in a difficult situation to manage: overreaching in its pressure could hand Trump the justification he needs to strike with greater force once control of both houses is lost on November 3.
A poorly explained war, an imprecise central bank, and Treasury buybacks too small to move the needle have exasperated fixed-income buyers. Some strategists are already referring to an “incompetence premium” impacting the pricing of U.S. sovereign debt.
Woodford, Warsh, and the Abandonment of Forward Guidance
This is why the coincidence surrounding Kevin Warsh’s abandonment of forward guidance—which likely affected the structure of the yield curve—and the Nobel Prize in Economics awarded to Michael Woodford, arguably the academic who put the most effort into establishing a theoretical foundation for that concept, remains curious. The award arrived last Monday, October 12, four months after Warsh dropped the concept in the FOMC statement on June 17. That said, the contradiction is smaller than it appears at first glance.
In Interest and Prices (2003), Woodford argued that monetary policy operates primarily through expectations of the future rate trajectory rather than the rate applied today. At Jackson Hole (2012), he extended that concept to zero-lower-bound (ZIRP) environments. His recommendation was to communicate guidance state-contingent on the economy rather than tied to a calendar date. The Fed implemented this in December 2012 by incorporating unemployment and inflation thresholds into the FOMC statement.
His subsequent work with García-Schmidt (2019) on economic agents planning over finite horizons significantly tempers the impact of long-term projections. Thus, within his own body of work, we find reasons to believe that guidance was less potent than the models suggested.
In reality, the disagreement with Warsh lies in substance, not form. For Woodford, what must be communicated is the central bank’s reaction function to incoming data, not the path of interest rates. Warsh states that guidance has “outlasted its usefulness” and offers instead a “framework” or “roadmap,” provided it is not termed forward guidance. This closely aligns with abandoning the rate trajectory while retaining the reaction function—which is precisely what Wall Street requested.
Furthermore, an important nuance exists: Woodford advocated guidance as a tool specifically when rates are at zero. With federal funds at 3.75–4%, its marginal utility is significantly lower. Therefore, in my view, extrapolating what occurred post-COVID (in 2021, the issue lay in committing to a rate path in an unprecedented environment amid runaway inflation) with Powell’s “transitory inflation” commentary and the resulting loss of credibility would be a mistake.
What occurred then does not prove that communicating the Fed’s reaction function to the market is useless. The risk lies in leaving the market to guess it, which inherently increases uncertainty, noise, and volatility in the fixed-income market.
In summary, the Fed’s reaction function is the rule, explicit or implicit, that translates the state of the economy into a rate decision. Communicating it means telling the market how the Fed decides, without promising what it will do.
Communicating the reaction function establishes the rule: the market continues to react to data, but in the direction and magnitude intended by the Fed—exactly what Woodford advocated. The question with Warsh is whether, in removing guidance, he will also cease to communicate the rule.