Financial markets can spend weeks, months, or even years incorrectly valuing a company. For Bill Ackman, founder and CEO of Pershing Square Capital Management, this discrepancy between a stock’s price and the economic value of its business is not necessarily a problem: it can become an investment opportunity.
The key lies in distinguishing when a company faces genuine deterioration in its outlook versus when the market is overreacting to a temporary event, an uncertain threat, or an unmet short-term expectation.
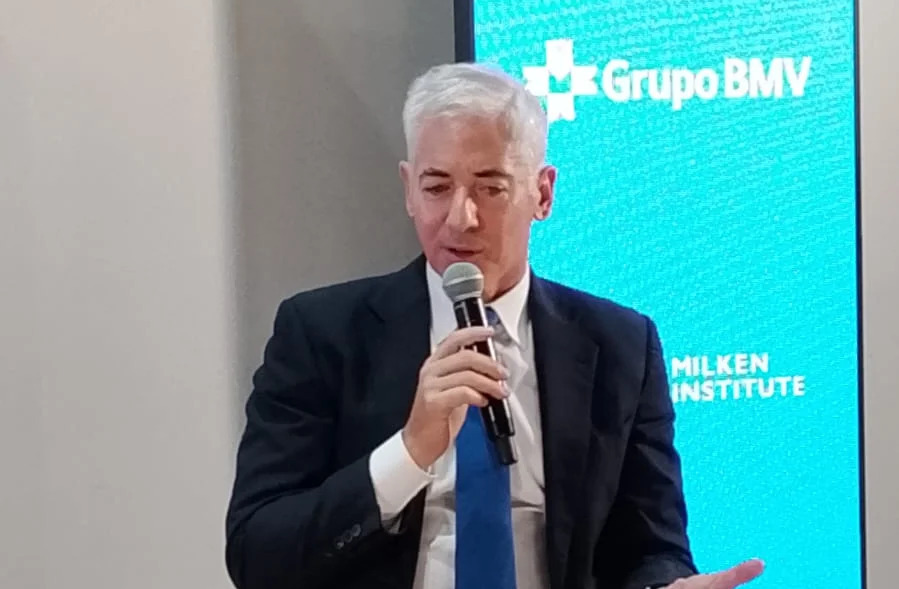
This forms one of the central tenets of Ackman’s investment philosophy, shared during his visit to the Mexican Stock Exchange (BMV), where he participated in the opening bell ceremony and met with media representatives.
The American investor, whose firm manages more than $30B in assets, outlined a framework combining the selection of companies with durable competitive advantages, the discipline not to pay any price, and the willingness to wait until market conditions offer attractive risk-adjusted upside.
This perspective is especially relevant in an environment characterized by heightened volatility, sharp price swings, and rapid sector rotations shifting from investor favorites to sell-off targets.
Ackman noted that short-term speculation risks pulling markets away from their core economic purpose: providing capital for businesses to expand.
A company, he reiterated, is a long-term asset, even if its shares change hands daily.
The difference between this outlook and that of traders seeking to capture moves over hours, days, or weeks is central to Pershing Square’s approach. Rather than chasing momentum, the firm identifies businesses capable of compounding value over years and waits for an entry price that captures that upside.
Uber: when fear creates opportunity
The clearest example Ackman cited was Uber, the mobility and delivery platform in which Pershing Square invested in early 2025.
The firm had tracked the company prior to its IPO, but did not view its market valuation as sufficiently compelling. That changed when the share price fell to levels that, in the firm’s assessment, adequately compensated for the investment’s underlying risks.
Part of the market’s concern centered on autonomous vehicles and the risk that manufacturers such as Tesla could roll out competing robotaxi networks capable of displacing Uber.
Ackman arrived at a different conclusion: the arrival of autonomous vehicles would not necessarily dismantle the platform’s competitive position, particularly if multiple vehicle manufacturers and operators coexist.
The underlying thesis holds that riders will continue to value the convenience of hailing rides from a single app, with speed, competitive pricing, and brand trust. From this standpoint, Uber could preserve its role as a key distribution layer between riders and mobility providers, even as technology shifts vehicle operations.
The investment did not rest on denying that autonomous driving could transform transportation. It hinged on assessing whether that shift would erode Uber’s network moat or integrate into an ecosystem where the platform retains structural pricing and aggregation power.
The logic illustrates a broader principle: a disruptive technological threat does not automatically destroy value across every incumbent in an industry.
The decisive question is where each business sits following the transformation, and whether its competitive moat remains wide enough to sustain durable growth.
A library of businesses, not a momentum chase
The Uber transaction illustrates another element of the strategy: investment opportunities do not simply begin when a stock pulls back. The most critical work takes place well beforehand, through systematic tracking of exceptional businesses.
Pershing Square targets dominant businesses across their industries, characterized by robust unit economics, multi-year growth runways, and moats capable of withstanding prolonged disruption. Regulatory risks and management caliber are assessed with equal rigor.
A business can meet every operational benchmark yet remain an unattractive investment at the wrong valuation. For this reason, the firm maintains a watchlist of high-conviction companies, waiting for catalysts that compress trading multiples: disappointing quarterly earnings, cyclical headwinds, or macro events that temporarily depress investor sentiment.
The discipline requires separating deterioration in business fundamentals from broader price volatility.
The firm favors cash-generative businesses with durable moats, conservative balance sheets, limited dependence on capital markets, and market prices trading at a discount to intrinsic value, alongside strong governance and management execution.
The objective is not merely buying cheap securities, but identifying high-quality compounders offering a margin of safety.
A depressed valuation multiple does not ensure an undervalued security; it may reflect structural obsolescence, competitive decay, or permanently impaired margins. The opportunity emerges when the market discount overshoots what is warranted by fundamental risk.
Evaluating that gap requires patience, deep business understanding, and analytical conviction, rather than a speculative bet on multiple mean-reversion.
The cost of short-termism
The critique of short-term market speculation carries a broader structural implication: when stock prices overreact to transitory news, long-term allocators can capture mispricings that shorter-horizon market participants cannot exploit.
Markets comprise allocators with divergent mandates and constraints. While some compound capital over multi-year horizons, others operate under tight drawdown mandates, leverage constraints, or liquidity requirements that force programmatic selling during drawdowns.
The takeaway is not that markets are perpetually inefficient or that every pullback represents a buying opportunity. Rather, price action must be scrutinized strictly against corporate fundamentals rather than recent trading momentum.
This underscores the necessity of establishing a validated investment thesis before market dislocation occurs. When an equity sells off, the allocator must determine whether the market is offering a discounted entry into a resilient business or correctly pricing fundamental deterioration not yet reflected in trailing financial statements.
Making that distinction demands more than volatility tolerance: it requires rigorous corporate analysis, scenario modeling, and an awareness of one’s circle of competence.
Capital structure matters
Investment performance is not solely a function of asset selection. Organizational culture and capital stability are equally critical to executing a concentrated, long-duration strategy.
Building an enduring investment institution begins with talent. Investment management relies fundamentally on culture, retention, and assembling teams that compound institutional knowledge over extended horizons.
Equally vital is structuring capital with permanent or long-dated duration.
Developing exchange-listed investment vehicles broadens investor access to the strategy. An investor can purchase a single share of Pershing Square USA for approximately $40, participating in vehicle performance under identical fee and liquidity terms alongside larger institutional allocators.
This structure delivers dual advantages: democratizing access to institutional asset management while providing a permanent capital base that allows positions to be held through market dislocations without exposure to redemption-driven liquidity crunches.
Permanent capital does not eliminate loss risk or ensure positive returns. However, it prevents portfolio decisions from being dictated by external liquidity constraints unrelated to portfolio company fundamentals.
In an approach predicated on waiting for the right entry multiple and compounding through the investment lifecycle, capital duration is as pivotal as asset selection.
Artificial intelligence: opportunities and disruption
Artificial intelligence represents another critical consideration for fundamental investing. While the technology is set to reshape broad swaths of the economy, it introduces distinct risks alongside significant commercial opportunities.
The analytical challenge extends beyond picking early technological winners. Allocators must evaluate which legacy businesses can leverage AI to widen their moats, and which face margin compression or technological obsolescence.
This mirrors the framework applied to Uber: technological disruption can redefine an industry without necessarily eliminating incumbent network aggregators. The ultimate outcome depends on market position, adaptability, and fundamental unit economics.
AI applications across healthcare and neuroscience present considerable potential to extend lifespans, improve diagnostics, and advance clinical therapies, with broad implications for long-term labor productivity and scientific research.
However, secular technological tailwinds do not automatically make every company touching AI a viable investment. Valuation multiples remain paramount, as does the ability to convert technological innovation into durable revenue, margins, and free cash flow.
AI does not suspend traditional valuation discipline; it makes it more essential. As technological uncertainty rises, the ability to separate aggregate industry hype from cash-generative corporate moats becomes the central investment hurdle.
Mexico and Latin America in a fragmented global economy
While the strategy centers on North American large caps, macroeconomic and geopolitical developments are shifting economic dynamics across Mexico and the broader region. Rising geopolitical frictions, international conflicts, and the push to reshore manufacturing to North America are altering where multinational corporations deploy capex and structure supply chains.
Within this framework, Mexico is well positioned to benefit from geographic proximity to the U.S. and deepened regional economic integration, underpinned by the structural alignment between both economies.
Key structural advantages include strategic geography, an entrepreneurial demographic profile, an established industrial manufacturing footprint, and an expanding domestic pension system capable of channeling long-term institutional capital into local infrastructure and economic growth.
Sustaining this trajectory requires stable domestic policy, including transparent legal frameworks that incentivize private investment and entrepreneurship, alongside ongoing efforts to improve public security.
Local equity valuations in Mexico appear optically low, though establishing specific allocations requires detailed corporate-level due diligence.
Evaluating local opportunities remains ongoing, with inbound investment proposals subject to institutional due diligence before determining whether they warrant capital deployment.
Capital relationships across the region continue to deepen, having raised hundreds of millions of dollars from Mexican institutional allocators—including single and multi-family offices, pension funds (AFOREs), and institutional insurers—across both management company structures and public vehicle offerings.
This dynamic reflects broader North American economic alignment, where long-term interests across the U.S., Mexico, and Canada converge around regional productivity, trade integration, and economic security.
The discipline of patience
Fundamental investing offers no mechanical certainty for timing market inflection points. Long-term returns depend on assessing terminal business values, executive capital allocation, and shifting technological, regulatory, and macroeconomic variables.
Yet the core principle remains consistent: durable compounding is not achieved merely by identifying leading businesses, but by demanding an entry price that provides an adequate margin of safety, backed by the balance sheet duration to hold through cyclical volatility.
In an asset management landscape that frequently overvalues trading velocity, institutional outperformance requires upfront fundamental research, systematic watchlist monitoring, and the patience to deploy capital only when market dislocations present asymmetric upside.
Uber highlights this approach. It did not require discovering an obscure asset or predicting the full trajectory of autonomous mobility. It required understanding the network model, analyzing technological risk, and waiting for market sentiment to compress the valuation to an attractive entry point.
The distinction between chasing market momentum and executing a fundamental strategy often crystallizes in that window: when the market prices in existential risk, and rigorous analysis reveals an asymmetric investment opportunity.
Patience is not passive waiting; it is conducting exhaustive upfront research, isolating the economic drivers of a company’s moat, and maintaining the discipline not to deploy until market price provides a margin of safety.