In a context in which private equity has failed to reach the performance of public equities, returning below the S&P 500 and the MSCI ACWI over one, three, and five years, the question regarding the value of the illiquidity premium is once again on the table. The fact is there is a question hanging in the air: Is there still room to generate alpha in the asset class? Especially in North America, where the United States remains the largest and deepest market for private capital.
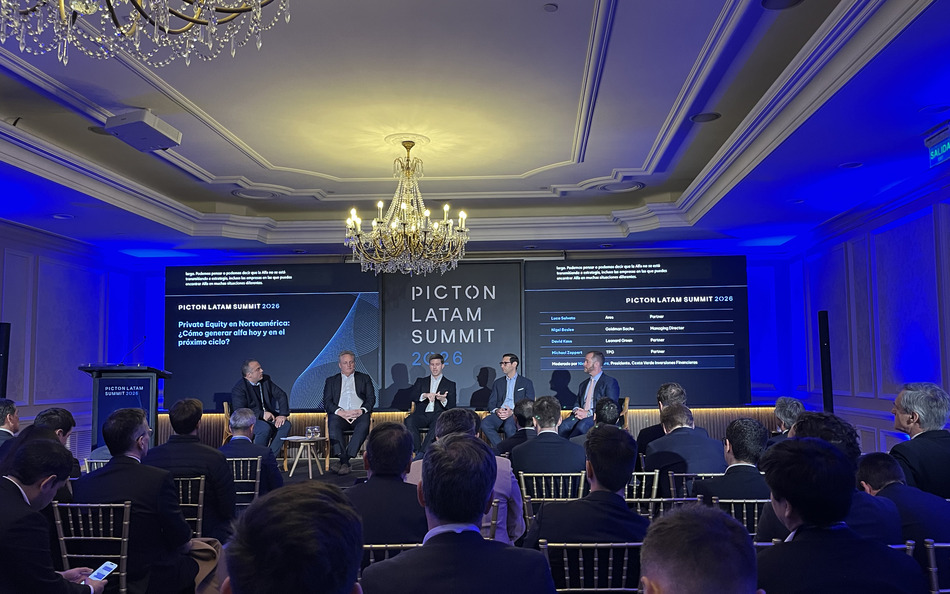
This is the question that brought together a panel of specialists from major specialized asset managers, convened by the Latin American distribution firm Picton, at the latest edition of its Latam Summit. Before an audience of GPs and LPs from various corners of the region, investment professionals outlined a landscape in which everyone is competing for the most attractive assets and dispersion is forcing investors to be more selective.
“There is performance, but you have to look at where to be,” said Nigel Beslee, Managing Director at Goldman Sachs. There is a major positioning challenge for investors, with the task of allocating conscientiously across different asset classes, against a backdrop of high uncertainty, significant market movements, and a technology narrative that is dictating the pace of trading desks globally.
“Nobody is aiming for median returns in PE,” the executive emphasized, as everyone is hunting for the highest returns.
“Rather than themes like sector or strategy, it is company-specific factors that drive alpha,” recalled Luca Salvato, Partner at Ares. In addition, there is the factor of certain “existential risks,” such as the AI revolution, which are difficult to quantify in a historical context given their nature as an unprecedented technology.
Against this backdrop, the professional emphasized market timing. “The timing in which a manager decides to sell the asset can generate a lot of alpha,” he assured.
The Technological Revolution
While private capital and public equity have different dynamics and characteristics, the professionals on the panel warned that private equity faces the challenge of beating a public equity market that has periodically been reaching new highs in recent years. This is mainly thanks to the effect of the stocks known as the Magnificent Seven—Alphabet, Amazon, Apple, Meta Platforms, Microsoft, Nvidia, and Tesla—which group together the firms considered captains of the AI boom.
Between that and an ecosystem where investment cycles are increasingly longer, investors must find ways to access growth vectors at reasonable prices. “There is a massive trend of private for longer, especially in high-growth tech companies,” said Michael Zappert, Partner at TPG, so LPs must carefully evaluate how to access this category.
In that regard, those in the PE industry see an interesting source in the application of this technology within their portfolio companies. This, Zappert noted, can generate significant value, as “AI is going to change every aspect of work.”
Since it is currently difficult to access the major tech firms leading on this front, the professional does see more opportunities in this wave of application.
Beslee agreed with the reading, highlighting that it is “difficult” not to see AI as one of the largest market factors; while Salvato added that, although this technology will not necessarily be a major generator of alpha in the asset class, it will undoubtedly boost the companies they invest in.
Increasing Diversity of Structures
In addition to creativity in capturing AI tailwinds, the current context forces GPs to be more creative with the structuring of investment vehicles as well. “It’s about being thoughtful about the spaces where you can do something different,” in the words of Zappert; while Salvato emphasized that one cannot deny the importance of managers in asset management, given the increased sophistication of the environment in North America.
All panelists commented on their experiences applying this greater flexibility, as is the case with Leonard Green. David Kass, Partner at the firm, recounted that at the company they have had to remain flexible with the structuring of vehicles when the assets are good and fit with the firm’s investment philosophy.
Different avenues can even be pursued to invest in a diversified manner within the asset class. In the case of Goldman Sachs, they highlighted the GP Stakes strategy, which invests in stakes of specialized asset managers.
The Importance of Liquidity
In any case, professionals agree that liquidity will continue to be one of the key variables going forward in the world of private capital. “There is massive pressure for liquidity,” said Zappert, especially with the strong influx of capital that the asset class recorded in 2021. The prevailing trend in portfolios, he stressed, is toward having a higher level of liquidity, not less.
For that reason, a space that has opened up strongly is that of secondary funds and continuation vehicles, which have created new liquidity spaces for PE managers. The industry is focusing on DPI (Distributed to Paid-In Capital, the ratio of distributions to invested capital), commented Kass, so distributions generate their own pressure on portfolio management. “At some point, you have to generate liquidity,” he said.
Looking ahead, Salvato added, continuation vehicles “are here to stay” and “are becoming an important part of the ecosystem.” However, he warned, this space also features a high level of dispersion in results.