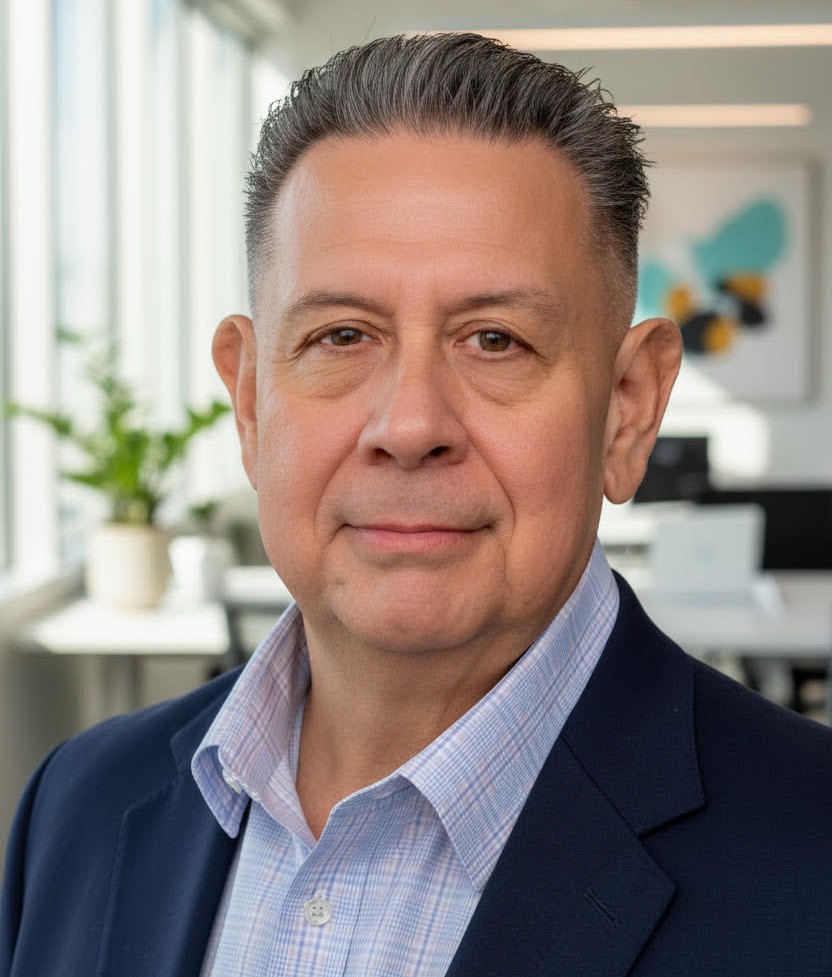
Macro and geopolitical uncertainty, interest rates that have stayed higher for longer and high index concentration are testing investors and their advisors alike. Now artificial intelligence is adding a new source of noise to the advisory relationship – “and clients are really listening to AI”, warns José Corena, Managing Director of the Americas at MFS Investment Management. In an exclusive interview with Funds Society, Corena explains why Latin American investors are unlikely to fall out of love with fixed income, and why liquidity concerns suggest private markets may already have peaked: “We have probably already seen a peak in private credit and private equity.”
Corena also makes the case for active management, highlighting MFS Meridian Funds – Contrarian Capital Fund and the firm’s Blended Research range, which combines fundamental and quantitative research. He also discusses the expansion of MFS’ active ETF line-up and what it takes to get new products onto distribution platforms.
Finally, he reflects on a year of change in MFS’ regional team, which spans Chile, Uruguay, Brazil, Colombia, Miami, New York, Texas and the U.S. West Coast, and explains why having people on the ground remains central to its strategy.
With markets this complex, what are clients really asking for?
Simple: they don’t want to lose money. That sounds straightforward, but markets have become far more complex. Geopolitical fragmentation is reshaping trade and investment decisions, interest rates have stayed higher for longer than expected, and a handful of stocks now dominate the major indices. When so much of the market rests on so few names, owning the index is not quite the safe harbour it seems – and research, selectivity and genuine diversification start to matter a great deal more.
On top of that, AI is adding another layer of noise between advisors, their teams and their clients – and clients are really listening to it.
Latin American investors have long had a love affair with fixed income. Is it still justified?
Very much so. Latin American investors will always have a soft spot for fixed income, and today the asset class is giving them good reason. After years of near-zero rates, bonds are once again offering something investors had almost forgotten about: meaningful income. For clients, that combination of income, diversification and liquidity is hard to ignore.
Some investors have been looking for that income in private credit. But I think we have probably already seen a peak in private credit and private equity. Clients are increasingly asking what they are really being paid to lock up capital for seven or ten years, and in our view the reward for illiquidity has been shrinking. Public credit, by contrast, offers attractive yields and solid fundamentals – and you can get your money back when you need it.
That doesn’t mean fixed income is a market to own blindly. Not every borrower is equally well placed, so research and careful credit selection make a real difference. Each country also has its own dynamics. In Mexico, institutional investors have plenty of local fixed income opportunities, while Chile‘s pension reform could bring greater flexibility in asset allocation. But the common thread across the region is the search for reliable income without giving up liquidity.
MFS is a committed active manager. How are you responding to the shift towards passive?
We are a global active manager with more than 100 years of history, and we are fully committed to public markets. We don’t do alternatives, private credit or private equity. Instead, we focus on what we do best: active management across public equity and fixed income, allocating capital responsibly and always with a long-term lens.
That said, we recognise that investors have choices – between active and passive, and between vehicles, from traditional mutual funds to the growing area of active ETFs. We launched our first active ETFs in the U.S. in December 2024 and now have 13, covering U.S. and international equities as well as fixed income. They have been very well received, with assets of more than $3 billion, and tax-loss harvesting has been an important driver of demand.
Active management is here to stay, even if it increasingly sits alongside low-tracking-error strategies, active ETFs and passive products. The Magnificent Seven have done extraordinarily well, but that doesn’t mean the other 493 companies in the S&P 500 lack potential. Concentration doesn’t last forever. New competitors emerge, and AI is lowering the barriers to entry, which could accelerate that process. As market leadership broadens, active managers are well placed to find the next generation of leading companies.
Which strategies are standing out this year?
Two in particular – and on the surface they couldn’t be more different, which is exactly the point. One goes where other investors fear to tread; the other makes sure we don’t miss what the market has overlooked.
MFS Meridian Funds – Contrarian Capital Fund is built on a simple truth: markets change, but human nature doesn’t. When a company hits trouble – a management misstep, a supply-chain snag, a cyclical slump mistaken for structural decline – fear takes over and investors sell first and ask questions later. That is when perfectly sound businesses end up trading well below what they are worth. Our portfolio managers, Anne-Christine Farstad and Zahid Kassam, lean into that discomfort rather than run from it. As they like to put it, you buy where it hurts.
Buying cheap shares is the easy part; the real skill is telling a temporary setback from a permanent one. We don’t invest in certainty – we invest in probabilities. The lower the price we pay, the less needs to go right, so a margin of safety is non-negotiable. So is a strong balance sheet, which buys a company time to fix what went wrong. When the dust settles and the fundamentals shine through again, that is when we believe the share price can bounce back. The result is a concentrated portfolio, built stock by stock with no regard for benchmark weights. Notably, it has no technology exposure today – and that is no accident. Tech is the market’s favourite trade, and the valuations show it; there is nothing contrarian about paying top prices for what everyone already owns. Even so, since its launch in November 2024, the fund has outperformed its benchmark, the MSCI World Value Index, and passed US$1 billion in assets in less than two years.
Blended Research takes a very different route to the same destination – generating alpha for clients. Every stock gets two independent opinions – one from our fundamental analysts, one from our quantitative models – and we focus on the “intersection” stocks that both rate positively. Quantitative models tend to shine when markets are driven by momentum; fundamental research comes into its own when momentum fades. Together, they give us human judgement and machine discipline across a far broader universe of securities. Long before AI became the talk of every boardroom, we were putting people and models to work side by side: we launched our first Blended Research strategy in 2001, so this is a capability with a 25-year history. Different routes, same conviction – in today’s concentrated markets, the best opportunities are often where the crowd isn’t looking.
Fee-based advisory is growing in U.S. wealth management. Is Latin America following?
In the U.S. offshore business serving non-U.S. clients, advisors increasingly see the benefits of the advisory model. Larger teams are forming because they are building businesses around longevity and generational planning, not individual transactions.
Generational and technological change mean advisors need time to build relationships with clients and their wider families. But transactional business won’t disappear. I expect the two models to coexist – some clients will want an advisory relationship, others won’t – and we can serve both.
The Southern Cone faces a particularly tough transition from brokerage to advisory, and reaching U.S. levels of advisory penetration would be hard given how the independent ecosystem works. Independent brokers rely on trailers, or retrocessions, as their advisory fee, and they don’t have the scale or time to work with 15, 20 or 25 fund houses, so they focus on five or ten. There are advisory elements in their model, but it is not true advisory.
How do you get new products onto those platforms?
We have a dedicated team of relationship managers working across our U.S. domestic, international and global platforms. Platforms have become more selective. Many products were approved 20 or 25 years ago, so firms already have a large line-up to review. The question now is simple: what makes a new product distinctive enough to justify adding it?
On the independent side, platforms such as Insigneo – one of our largest clients in Latin America – matter a great deal, and Insigneo has been relatively open to new products. Launching in the Southern Cone can also help us build scale, which in turn strengthens the case for those products with U.S.-based clients. We have some distinctive strategies coming to market, and we hope they will reach the critical mass needed for approval.
It has been a year of change for your regional team. What does that mean for the clients and advisors you work with?
It has probably been the year of most change for our team, and most of the moves were personal decisions. We are known for our low turnover as a firm, in both the investment department and even in distribution. Sometimes when long-tenured colleagues leave, it is a good reminder that change is constant.
What does not change is the continuity and the priority of having people on the ground. Advisors want a partner who understands their market, picks up the phone when markets get difficult and brings our global research to their clients’ portfolios. We want to be the people advisors call before they talk to their clients, not after.
Finally, what role will AI play in the future of investment and advice?
AI is here to stay. I tell my team that AI will not replace us, because nothing can replicate face-to-face interaction – understanding the person and the relationship.
But if you are not using AI, you will be replaced. Used well, it can make us far more efficient.
The problem is that it adds to the enormous amount of noise we already get every day from social and mainstream media – and different platforms can give different answers. For example, we have seen advisors prepare detailed proposals, only for clients to upload them into an AI tool and ask whether they make sense. The answer can point to a passive solution, even when the whole conversation was about meeting an actively managed investment need.
That doesn’t make those recommendations right or wrong. But a machine cannot understand a relationship between an advisor and a client or family that may have been built over 20, 30 or 40 years. AI can read the document; it cannot understand the context behind the relationship.