From The Post-Election Rebound To The Collapse: A Forced Adjustment, Not A Broken Thesis
| By Amaya Uriarte | 0 Comentarios
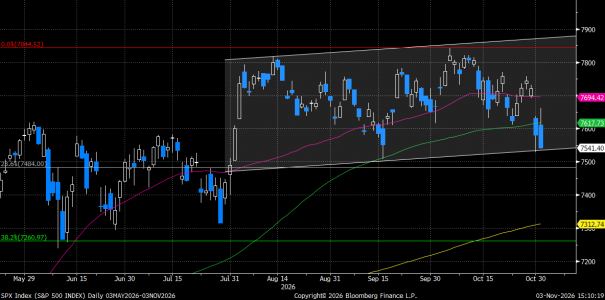
The Standard & Poor’s 500 Index stood, in the week of the midterm elections, at the lower support of the consolidation band that has contained its gains since August. As already happened in 2025, after the commercial launch of DeepSeek at the beginning of the year, Liberation Day, or the fears about circular financing in November, doubts around artificial intelligence were resurfacing, and with them, the fear of an imminent bursting of the bubble. The first reading of the election result was positive: on Wednesday, the United States stock market recorded its best session since the summer, and the hyperscalers rebounded strongly, decoupling from semiconductors and from the industrial subsectors tied to data center construction, which were more heavily penalized by the forcefulness of the Democratic victory.
The euphoria lasted one day. On Thursday, the market focused on what the Democratic majority could mean for the pace and cost of rolling out artificial intelligence infrastructure. The S&P 500 fell 4.4%, its worst session since April 2025, while the Nasdaq Composite lost 5.5% and entered a correction. The Philadelphia Semiconductor Index plunged 12%, the VIX rose nearly 70%, to 28 points, and all eleven sectors of the S&P 500 closed in negative territory. Added to the regulatory fear were some weak results in the semiconductor sector. The most visible catalyst was Texas, one of the country’s major data center hubs: the governor-elect, Gina Hinojosa, has pledged to freeze all new approvals until the legislature passes specific regulation in 2027, extending the pause that Abbott had already decreed in August.
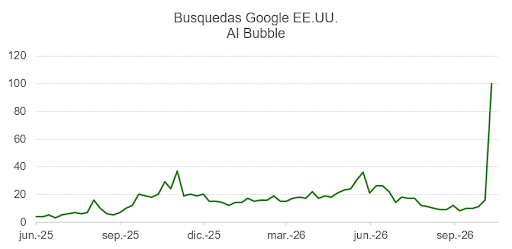
In our judgment, the move is more of a forced liquidation than a break in the thesis. Hedge funds had been cutting their gross exposure since June, by more than 8%, the largest deleveraging since at least 2017, according to Morgan Stanley, and when leverage is withdrawn, you sell what you can, not what you want. That many artificial intelligence beneficiaries already show declines of more than 20% from their highs seems disproportionate to us, given fundamentals that, for now, continue to improve. Nor do we anticipate a slowdown in artificial intelligence development or a national moratorium on data centers, which would put at risk the technological race with China and productivity growth. The news flow may get worse before it gets better, and deleveraging episodes are rarely resolved in a single session. But history is on our side: since 1950, the S&P 500 has traded higher twelve months after every midterm election. As we explain below, neither the bubble thesis nor the regulatory impact on computing supply justifies, in our judgment, the magnitude of the adjustment.
Bubble? Artificial Intelligence Adoption Still Has A Long Way To Go
Although the artificial intelligence investment cycle is advancing (the free cash flow of the hyperscalers is already in negative territory in most cases) and, unlike in 2025, the Federal Reserve is in the middle of a mini-cycle of rate hikes, interest rates have pressured multiples, which are much more reasonable than in 1999. Moreover, the recent correction has conveyed skepticism and caution toward a disruptive technology, not optimism, which dismantles, at least for the moment, the bubble hypothesis.
Investment as a percentage of gross domestic product may be frightening in its magnitude (it has already surpassed the peak reached in the internet era), but the adoption of the technology still has a long way to go. To confirm this, we look at data from Ramp AI (which only counts those who use paid services, but focuses on a universe of just 85,000 companies and whose sample is biased toward technology and growing companies) and from the United States Census Bureau (BTOS), a much broader survey that incorporates up to 1.2 million companies, but only asks about use, which may include free services. Ramp serves us to analyze the pace of growth and which laboratories gain or lose market share. The BTOS is the best measure of how far the use of artificial intelligence tools has penetrated the business fabric, although it is published with a delay and is biased toward small and medium-sized businesses.
Nevertheless, the conclusion coincides in both cases: in September, the Ramp index shows a penetration of 55.9%, while the BTOS survey ranges between 17% and 20% (among companies with more than 250 employees it reaches 37%). Outside the realm of surveys, which always present biases, Anthropic’s S-1 that we referred to last week showed that Fortune 500 companies devote less than 0.1% of their total spending to Claude.
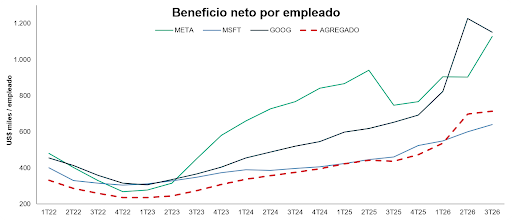
Since 2025, and also according to Ramp data, spending per employee on artificial intelligence applications has multiplied by six, although it has only really begun to accelerate in the last ten months. The effect of these tools on productivity, as well as their reflection in the profits of the large hyperscalers, is evident in this chart.
Demand For Computing Power Continues To Exceed Supply
As we explained last week, there is clear evidence that demand for computing power continues to strengthen and, for the moment, exceeds supply. The hourly rental price of Nvidia’s H100 (Hopper generation), with one-year contracts, has risen 60% in the last year, and that of the Blackwell has also become more expensive.
If a server with extremely expensive accelerators quickly stops being profitable for training frontier models or for offering truly competitive inference prices, the return on invested capital of that investment is compromised. In addition, the release cadence of increasingly powerful chips has increased. The other side of the coin is that, to stay at the forefront of this race and gain market share with more competitive prices in artificial intelligence services without sacrificing margin, you have to invest in cutting-edge technology. An Nvidia GB300 NVL72 rack processes about 6,000 tokens per second on each of the 72 graphics processing units it incorporates, compared to about 90 with the previous generation (Hopper); that is, about 65 times more. The new Vera Rubin, which will begin shipping in volume shortly, multiplies the capacity of the GB300 by between 2.5 and 3.5 times (about 15,000 tokens per second), although, adjusted for power consumption per watt, the improvement would be 1.3 to 1.6 times.
In addition, token usage is growing beyond the demand provided by the large artificial intelligence laboratories (Anthropic and OpenAI). Recent data show us that demand from artificial intelligence agents has already surpassed that of traditional users and has grown 14 times since February. Along the same lines, the use of mixture-of-experts models also increases the token load, and open models, which are cheaper, are being used more and more. The falling cost of tokens stimulates more intensive use of the models and drives up demand for computing power.
It is feasible that, as supply bottlenecks are cleared, the rental price of graphics processing units will fall more in line with their depreciation rate and with the launch of more powerful units. But we are not there yet. In the meantime, there is computing capacity contracted at spot prices per megawatt that will have to be revised upward in 2027-2028 (the contracts of AWS, Google, or Azure with Anthropic do not publish price terms, but CoreWeave’s 10-K states that the weighted average duration of its contracts is about 5 years).
The “Blue Wave” And Data Centers
The holding of the legislative elections in the United States removes one unknown to be resolved ahead of the close of 2026, and the strength of the “Blue Wave” exceeded the expectations of specialists and bookmakers. The speed at which Trump has consumed his political capital in his second term is surprising and has a lot to do with not having addressed the main concern of those who voted for him in 2024: inflation and the domestic economy. On the contrary, Trump embarked on a capricious and poorly explained war and on the imposition of high tariffs even on allied nations aligned with American commercial interests. It is an almost unprecedented defeat, in which Trump has lost control of Republican “fortress states,” such as North Carolina (the first time since 2008 that it has elected a Democrat to the Senate), Texas, or Florida (where Republicans have lost seats despite redrawing the electoral districts to their convenience). This result, a priori, and because of what it implies for the 2028 presidential elections (with new Democratic governors in states such as Ohio or Iowa, historic “swing states” that had passed into Republican control), reduces the risk of a new attack on Iran and shifts the focus of geopolitics toward the Federal Reserve and the sustainability of the earnings-per-share growth cycle.
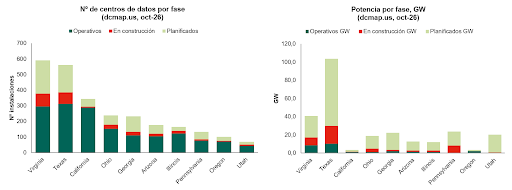
With results that are still provisional (at the time of writing, the results in Arizona, Oregon, Michigan, or Minnesota were still to be known), and as we see in the chart above, the electoral upheaval will also put the focus on the evolution of data centers under development and in the planning phase, as well as on possible delays affecting the supply of computing power. Opposition to the construction of data centers was seen in both red and blue states, with Republicans such as Abbott, who had already paralyzed new approvals in Texas in August. Nevertheless, the Democratic sweep sharpens the situation.
Texas (Democrat, Hinojosa), Georgia (Democrat, Bottoms), Ohio (Democrat, Acton), and Iowa (Democrat, Sand), in addition to Virginia (which passed into Democratic hands in 2025) and Pennsylvania, concentrate the bulk of the gigawatts planned and under construction: 189.5 gigawatts of the roughly 346 gigawatts projected.
In Pennsylvania (Shapiro), the developer must build, bring in, or buy its own power generation. In Ohio (Acton), the moratorium would be conditional: only data centers that pay for their energy and water and demonstrate that they do not raise their neighbors’ bills would be approved. In Virginia (Spanberger), a tax of 0.011 dollars per kilowatt-hour has been introduced, about 77 million dollars per year per gigawatt, with a load factor of 80%, while maintaining the sales tax exemption for equipment. Georgia (Bottoms) is the harshest case: it calls for a statewide pause and a review of the 2.5 billion dollars in tax incentives.
Nevertheless, the impact in 2026-2027 will be very low: in the four main states there are 25.9 gigawatts already under construction that would not be affected by a regulatory change, and Trump has already promised to become “Mr. Veto,” so he will possibly block any Democratic attempt at the federal level to increase the tax burden or tighten regulation on the construction of data centers.
If the White House passes into Democratic hands in 2028, the uncertainty will affect the 108.9 gigawatts planned in those states. In a base scenario, with subjective probabilities for each of them, around 10-15 gigawatts could be delayed. The effect would not be very significant: adjustments in state legislation would mean obstacles (unions, environmental requirements, and restrictions on electricity consumption), but not bans on construction.
The final idea: the electoral outcome increases the value of already installed computing capacity and should also sustain the hourly rental cost of graphics processing units and accelerators. Additionally, it could be the perfect excuse to slow the pace of investment. The hyperscalers are clear beneficiaries.